- 产品线沿革The product line
- 七项独家条款The seven exclusive riders
- Enhancer 系列:用费用换上限The Enhancer series
- 四种贷款方式Four ways to borrow
- 怎么选:三种典型情形Choosing: three typical cases
- 和六家主流 IUL 比:生前福利规格对照Against six other IULs
- LLD 不是每一项都赢Where LLD doesn't win
- 用这张对照表的四条规矩Four rules for the comparison
- 核保:LLD 和别的产品不一样的几条Underwriting: where LLD differs
Living Life Defender 是国家人寿 IUL 产品线的当前主力, 2023 年推出,2025 年更新至 2.0 版本。它的前身依次是 Living Life(2016)与 Living Life By Design(2019)。每一代的改进方向都很一致: 降低保单成本,增加条款灵活度,提高利息上限。
Living Life Defender is National Life's current flagship IUL, launched in 2023 and updated to 2.0 in 2025. Its predecessors were Living Life (2016) and Living Life By Design (2019). Each generation has moved in the same direction: lower policy costs, more rider flexibility, higher crediting ceilings.
一、产品线沿革1. The product line
带生前福利的 IUL 出现
IUL with living benefits
生前福利条款开始成为指数型万能寿险的标准配置。
Living benefit riders begin to be embedded into IUL as standard.
Living Life
第一代命名产品。
The first named generation.
Living Life By Design
条款结构与设计弹性进一步扩展。
Broader rider structure and design flexibility.
Living Life Defender
引入 Defender 系列的独家条款组合。
Introduces the Defender exclusive rider set.
Living Life Defender 2.0
当前在售版本,保单成本与费用进一步下降。
The current version, with further reductions in policy cost and expenses.
二、七项独家条款2. The seven exclusive riders
Combo Multi-Choice Rider (CMC)
允许为被保险人、或与其存在保险利益的其他个人,附加 20 年或 30 年的定期保险。 比另外单独购买一份定期寿险便宜,而且这份定期保险之后可以转换为 Living Life Defender。 更关键的是它能大幅提升 MEC 上限:在合规范围内,一年最多可以存入 $100 万用于长期理财。
Adds 20- or 30-year term coverage on the insured or another person with an insurable interest. Cheaper than buying that term separately, and it can later be converted into Living Life Defender. Most importantly it raises the MEC limit substantially: within the rules, it allows as much as $1M of funding in a single year for accumulation purposes.
规则要点:最多 5 人、合计最多主保额 3 倍;一人不符合某项生前福利,全体都失去这一项;20 年期要在 15 年内、30 年期在 20 年内转换。 可保利益和额度见《产品与附约速查》。
Key rules: up to five people and 3× the base face in total; if one person fails an ABR, everyone loses it; convert 20-year CMCs within 15 years and 30-year within 20. Insurable interest and limits are in Products & Riders.
Gap Protector Rider (GPR)
允许客户在需要时自动增加保额,无需重新核保。 人生阶段会变,比如再生一个孩子、换更大的房子、生意做大了, 这个条款让保额可以跟着需求走,而不必因为体检结果变差而被卡住。
Lets the client increase coverage automatically, without new underwriting. Life changes (another child, a bigger mortgage, a growing business), and this rider lets coverage follow the need instead of being blocked by a health change.
Extended Hospital Stay Death Benefit
如果被保险人连续住院至少 20 天后在医院去世,此条款额外支付 $5,000 理赔。 金额不大,但覆盖的是一段家属通常压力最大、开销也最密集的时期。
If the insured dies in hospital after at least 20 consecutive days of admission, this rider pays an additional $5,000. A small amount, but it lands in the window when a family's stress and out-of-pocket costs are highest.
Unemployment Waiver of Surrender Charge
如果被保险人连续失业 12 个月、且在提出请求时仍处于失业状态, 完全退保时的退保费用将被免除。这是一条"最坏情况"条款: 客户真走到必须动用这笔钱的地步,也不会在那个时候再被罚一笔。
If the insured has been unemployed for 12 consecutive months and is still unemployed when they request it, surrender charges on a full surrender are waived. This is a worst-case rider: if someone does have to reach for this money, they aren't penalized at that moment.
Guaranteed Flex Rider (GFR)
提供 10 年、20 年、30 年或 40 年的保证期, 在保证期内保单不会因现金价值不足而失效。10 年期免费,更长的期限收取少量月费。 这是对冲"断保风险"最直接的工具。
Provides a guarantee period of 10, 20, 30, or 40 years during which the policy won't lapse for insufficient cash value. The 10-year version is free; longer periods carry a small monthly charge. This is the most direct hedge against lapse risk.
Enhancer / Enhancer Plus / Enhancer Max
利息提升条款,不论保额多少都可以开启。 在很多同类产品上,高上限策略只对大保额客户开放; Defender 把这个门槛拿掉了。详见下一节。
Interest-bonus riders, available at any face amount. On many competing products the high-ceiling strategies are reserved for large cases; Defender removes that threshold. See the next section.
更低的保单成本与费用
Lower policy cost and expense
这一条听起来最不起眼,实际影响最大。保单成本每月从现金价值中扣除, 在 30 年的复利尺度上,存同样的钱,成本低一点, 累积的现金价值就高一截。
The least glamorous item on the list and the one with the largest effect. Policy charges come out of cash value every month, and over thirty years of compounding, a lower charge compounds into meaningfully more accumulation for the same premium.
三、Enhancer 系列:用费用换上限3. The Enhancer series: paying for headroom
基础 IUL 策略的封顶通常在 11% 左右。Enhancer 系列的作用, 是用一笔额外付费换取更高的利息奖金与更高的上限。三个档位的差别如下:
A base IUL strategy typically caps around 11%. The Enhancer riders trade an extra charge for a higher interest bonus and a higher ceiling. The three tiers:
| 条款Rider | 奖金比例 当前 / 保证Bonus rate current / guaranteed |
奖金上限 标普 500 当前 / 保证Bonus ceiling S&P 500 current / guaranteed |
额外付费Charge |
|---|---|---|---|
| Enhancer | 15% / 15% | 0.85% / 0.40% | 无None |
| Enhancer Plus | 45% / 20% | 2.50% / 1.50% | 1% |
| Enhancer Max | 第 2–20 年:95% / 30%Years 2–20: 95% / 30% | 6% / 2.50% | 第 1–19 年 3%3% years 1–19 |
| 第 21–30 年:70% / 25%Years 21–30: 70% / 25% | 4.25% / 2.00% | 第 20–29 年 2%2% years 20–29 | |
| 第 31 年起:45% / 20%Year 31+: 45% / 20% | 2.50% / 1.50% | 第 30 年起 1%1% from year 30 |
时间点要讲对:费用从保单第 1 年就开始扣,奖金从第 2 年才开始给。 表里的当前值是 2025 年 10 月的数字(波动控制策略的上限更高:Enhancer 0.95%,Plus 3.00%,Max 7% / 5% / 3%); 费用是固定的,奖金比例和上限可以下调,最低到保证值。完整对照见《产品与附约速查》。
Get the timing right: charges start in policy year 1; bonuses start in year 2. Current values are as of October 2025 (vol-controlled strategies have higher ceilings: Enhancer 0.95%, Plus 3.00%, Max 7% / 5% / 3%); the charge is fixed, while bonus rates and ceilings can be lowered to the guaranteed level. Full comparison in Products & Riders.
Enhancer 和「利息奖金」二选一。LLD 投保时要在两种结构里选一种,之后不能在两类之间换: 一种是上面的 Enhancer 系列(系列内每段结束时可以换档);另一种是不收费的利息奖金(Interest Bonus), 第 2–9 年 0.25%,第 10 年起多数指数策略 0.50%(Basic、Fixed 策略仍是 0.25%),按平均账户价值计,同样是当前值、非保证。 还要注意:开了 Enhancer,就不能选参与型分红贷款(见下一节)。
Enhancer or Interest Bonus, not both. LLD takes one of two structures at issue, with no switching between them later: the Enhancer family above (within which you can change tier at each segment end), or the free Interest Bonus, 0.25% in years 2–9 and 0.50% from year 10 on most index strategies (still 0.25% on Basic and Fixed), on average account value, likewise current and not guaranteed. Note too that an Enhancer rules out the participating declared loan (next section).
回测:用现在的参数算过去Back-tests: today's parameters applied to the past
培训里常用两组回测,都是把现在的参数套到历史标普涨跌上,不是当年真实存在的保单。 IUL 各列只扣了附约费用,没扣保险成本和保单费用,真实现金值会更低;标普一列是价格涨幅,不含分红、也不扣基金费用。 两边口径不同,只能用来解释机制,不能当成回报率比较。
Two back-tests come up in training. Both apply today's parameters to historical S&P moves; neither is a policy that existed at the time. The IUL columns deduct only rider charges, not insurance or policy costs, so real cash values would be lower; the S&P column is price return, with no dividends and no fund fees. The bases differ, so use them to explain mechanics, never as a comparison of returns.
| 2004 年存 $10 万$100,000 in 2004 | 标普 500S&P 500 | 利息奖金Interest Bonus | Enhancer | Plus | Max |
|---|---|---|---|---|---|
| 2008 年末End of 2008 | $74,525 | $119,883 | $120,406 | $119,486 | $116,765 |
| 2024 年末End of 2024 | $485,291 | $441,487 | $457,987 | $464,974 | $471,946 |
| 20 年年化(扣附约费用后)20-year annualized (after rider charges) | 8.22% | 7.71% | 7.91% | 7.99% | 8.07% |
| 每年记息的波动率Volatility of annual crediting | 17.07% | 4.97% | 5.35% | 6.49% | 8.87% |
这一组要诚实地读:二十年下来,标普的数字比 IUL 各列都高;IUL 换来的是 2008、2022 这类年份不跟着跌, 一路上起伏小得多(波动率 5%–9%,标普 17%)。Plus、Max 在指数为 0 的年份会因附约费用记成 −1%、−3%。
Read this one honestly: after twenty years the S&P finishes above every IUL column. What the IUL buys is not falling in years like 2008 and 2022, and a much smoother path (volatility of 5–9% against 17%). In a zero-index year Plus and Max show −1% and −3% because of the rider charge.
另一组是常见的「1997 年同时存 $10 万」。起点紧挨着 2000–2002 和 2008 两次大跌,对 IUL 特别有利,换一个起点结论会不同。 LLD 一列按封顶 11% 加 Enhancer 加成(最多 0.85%)计;LLD + Max 一列按最多 17% 记息、每年扣 3% 费用计。 若对标普的增值按 20% 计税,2023 年税后约 $413,183;保单内是延税,以保单贷款取用、且保单维持到身故,才不产生所得税。
The other is the familiar "$100,000 in 1997." Its start sits just before the 2000–2002 and 2008 crashes, which favours the IUL; another start date gives a different answer. The LLD column uses the 11% cap plus the Enhancer bonus (up to 0.85%); LLD + Max credits up to 17% less a 3% annual charge. If the S&P gain is taxed at 20%, it nets about $413,183 in 2023; inside the policy growth is tax-deferred, and is free of income tax only if taken as policy loans with the policy kept in force to death.
| 年份Year | 标普 500 点对点S&P 500 pt-to-pt | 标普累计S&P value | LLD 记息LLD credit | LLD 累计LLD value | LLD + Max 记息LLD + Max credit | LLD + Max 累计(扣 3%)LLD + Max value (−3%) |
|---|---|---|---|---|---|---|
| 1997 | — | $100,000 | — | $100,000 | — | $100,000 |
| 1998 | 26.67% | $126,670 | 11.85% | $111,850 | 17.00% | $114,000 |
| 1999 | 19.53% | $151,409 | 11.85% | $125,104 | 17.00% | $129,960 |
| 2000 | −10.14% | $136,056 | 0.00% | $125,104 | 0.00% | $126,061 |
| 2001 | −13.04% | $118,314 | 0.00% | $125,104 | 0.00% | $122,279 |
| 2002 | −23.37% | $90,664 | 0.00% | $125,104 | 0.00% | $118,611 |
| 2003 | 26.38% | $114,581 | 11.85% | $139,929 | 17.00% | $135,217 |
| 2004 | 8.99% | $124,882 | 10.34% | $154,398 | 17.00% | $154,147 |
| 2005 | 3.00% | $128,629 | 3.45% | $159,724 | 5.85% | $158,540 |
| 2006 | 13.62% | $146,148 | 11.85% | $178,652 | 17.00% | $180,736 |
| 2007 | 3.53% | $151,307 | 4.06% | $185,905 | 6.88% | $187,748 |
| 2008 | −38.49% | $93,069 | 0.00% | $185,905 | 0.00% | $182,116 |
| 2009 | 23.45% | $114,894 | 11.85% | $207,935 | 17.00% | $207,612 |
| 2010 | 12.78% | $129,577 | 11.85% | $232,575 | 17.00% | $236,678 |
| 2011 | 0.00% | $129,577 | 0.00% | $232,575 | 0.00% | $229,577 |
| 2012 | 13.41% | $146,953 | 11.85% | $260,135 | 17.00% | $261,718 |
| 2013 | 29.60% | $190,451 | 11.85% | $290,961 | 17.00% | $298,359 |
| 2014 | 11.39% | $212,144 | 11.85% | $325,440 | 17.00% | $340,129 |
| 2015 | −0.73% | $210,595 | 0.00% | $325,440 | 0.00% | $329,925 |
| 2016 | 9.54% | $230,686 | 10.97% | $361,141 | 17.00% | $376,114 |
| 2017 | 19.42% | $275,485 | 11.85% | $403,936 | 17.00% | $428,770 |
| 2018 | −6.24% | $258,295 | 0.00% | $403,936 | 0.00% | $415,907 |
| 2019 | 28.88% | $332,890 | 11.85% | $451,803 | 17.00% | $474,134 |
| 2020 | 16.26% | $387,018 | 11.85% | $505,341 | 17.00% | $540,513 |
| 2021 | 26.89% | $491,087 | 11.85% | $565,224 | 17.00% | $616,185 |
| 2022 | −19.44% | $395,620 | 0.00% | $565,224 | 0.00% | $597,699 |
| 2023 | 24.23% | $491,479 | 11.85% | $632,203 | 17.00% | $681,377 |
回算,非保证:用现在的产品参数回算历史,不是当年真实存在的保单。
Back-cast, not guaranteed: today's product parameters applied to history, not a policy that existed then.
Enhancer Max 在第 1–19 年收取 3% 的额外费用。 在指数表现好的年份,95% 的额外利息增长远远覆盖这笔费用; 但在指数连续为 0% 的年份,这 3% 是净流出:你付了费用,却没有额外利息可拿。 所以选 Enhancer 档位,等于对"未来 20 年指数表现"下一次判断, 应该结合客户的风险承受度与缴费能力来定,而不是默认选最高档。
Enhancer Max charges 3% in years 1–19. In strong index years the 95% bonus far outweighs it, but in a string of 0% years that 3% is a net outflow: you pay the charge and receive no bonus. Choosing an Enhancer tier amounts to a judgment about the next two decades of index behavior, and should follow from the client's risk tolerance and funding capacity rather than defaulting to the highest tier.
Defender 独家条款的另一项作用,是把任何保额的封顶上限提高到最高 17%。 在传统产品上,这类高上限策略通常有保额门槛。
A further effect of the Defender exclusives is that any face amount can access a cap ceiling of up to 17%. On traditional products, high-ceiling strategies usually come with a face-amount threshold.
四、四种贷款方式4. Four ways to borrow
保单贷款是把现金价值拿出来用的主要方式:只要保单维持到身故,贷款不产生所得税;中途断保,之前取的钱要补税。 国家人寿提供四种贷款类型,它们在利率、风险和收益上的取舍完全不同:
Policy loans are the main way to use the cash value: as long as the policy stays in force to death, loans create no income tax; if it lapses, what was taken becomes taxable. National Life offers four loan types, each with a different balance of rate, risk, and upside:
| 贷款类型Loan type | 利率Rate | 贷出金额是否继续计息Borrowed amount keeps earning? |
|---|---|---|
| Standard Loan 标准贷款Wash loan |
前 10 年净成本 0.5%;第 11 年起贷款利率与返还利率持平,净成本为 0(常说的「无息」指的是这一段)0.5% net cost in years 1–10; from year 11 the loan rate matches the rate credited back, for zero net cost (what people call "interest-free" is this stage) | 否No |
| Participating Fixed Loan 参与型固定利息贷款Index loan, fixed rate |
固定每年 5%,上限 5%Fixed 5% per year, capped at 5% | 是Yes |
| Participating Variable Loan 参与型浮动利息贷款Index loan, variable rate |
随穆迪公司债券指数变化,上限为基础策略利率 + 3%,上限本身也会变,没有固定封顶(资料时点约 6%,《保单贷款》成稿时 6.5%)。资料时点约 5.4%,疫情期间最低曾至 2.3%Tracks the Moody's corporate bond index, capped at the base crediting rate + 3%; that ceiling moves too, so there is no fixed cap (about 6% in the training material, 6.5% when Policy Loans was written). Around 5.4% in the material; it fell as low as 2.3% during the pandemic | 是Yes |
| Participating Declared Loan 参与型分红贷款Index loan, declared rate |
由国家人寿决定,上限 8%,资料时点约 5.5%(《保单贷款》成稿时 6.25%);贷款金额可获额外 0.35% 利息;开了 Enhancer 不能选Declared by National Life, capped at 8%, around 5.5% in the training material (6.25% when Policy Loans was written); the borrowed amount earns an extra 0.35%; not available with an Enhancer | 是Yes |
参与型贷款的逻辑:你借出去的钱仍然留在保单内参与计息。 如果今年指数增长高于贷款利率,你拿到了现金,被贷出的那部分也还在继续赚钱,这叫正套利。 但反过来,如果指数当年为 0%,你仍然要支付贷款利息,这时就是负套利。 参与型贷款放大了收益,也放大了风险。
How participating loans work: the borrowed amount stays in the policy and keeps earning. If the index credits more than the loan rate that year, you have the cash and the borrowed balance is still growing. That's positive arbitrage. But if the index credits 0%, you still owe the loan interest, and the arbitrage runs against you. Participating loans amplify both the upside and the risk.
表里的利率都是某一时点的数字,随时会变,用之前查一次当期利率表。四种贷款的算例和怎么选,见《保单贷款》。
The rates in the table are point-in-time figures and change; check the current rate sheet before using them. Worked examples and how to choose are on the Policy Loans page.
五、怎么选:三种典型情形5. Choosing: three typical cases
保障优先
Protection first
家里有房贷、孩子还小、预算有限。重点在把保额做够, 搭配 Guaranteed Flex Rider 保证不断保,Enhancer 选基础档即可。 CMC Rider 可以用更低的成本补足短期保额缺口。
Mortgage, young kids, limited budget. Prioritize face amount, pair it with the Guaranteed Flex Rider so the policy can't lapse, and keep Enhancer at the base tier. The CMC rider fills the short-term gap at lower cost.
积累优先
Accumulation first
现金流稳定、已有其他保障、目标是退休免税现金流。 保额做到税法允许的最低水平以降低成本,Enhancer Plus 或 Max 提高上限, 用 CMC Rider 提升 MEC 空间以便多存。
Stable cash flow, coverage already in place, goal is tax-free retirement income. Keep the face amount at the minimum the tax code allows to reduce cost, use Enhancer Plus or Max for headroom, and use the CMC rider to raise the MEC limit so more can go in.
保单升级
Policy upgrade
已有一张旧的 WL / UL / 早期 IUL 保单。 可以评估通过 1035 Exchange 把现金价值免税转入新保单, 在不增加额外税负的前提下拿到更低的保单成本与更全的条款。
An older WL / UL / early IUL policy already exists. A 1035 exchange can move the cash value into a new contract tax-free, picking up lower policy costs and a fuller rider set without triggering tax.
1035 Exchange 不是无脑升级。新保单会重新开始计算退保费用期, 核保也要重新做,如果被保险人健康状况变差,新保单的费率可能更贵,甚至无法通过。 旧保单上的某些条款(例如已锁定的保证利率)也可能一去不返。 必须逐单比对之后再决定,不能只看封顶数字。
A 1035 exchange is not an automatic win. The new contract restarts the surrender charge period and requires fresh underwriting; if health has declined, rates may be worse or the case may be declined outright. Certain features on the old contract, such as a locked-in guaranteed rate, are gone for good. Compare the contracts line by line before deciding; the cap alone tells you nothing.
六、和六家主流 IUL 比:生前福利规格对照6. Against six other IULs: the living-benefit specs
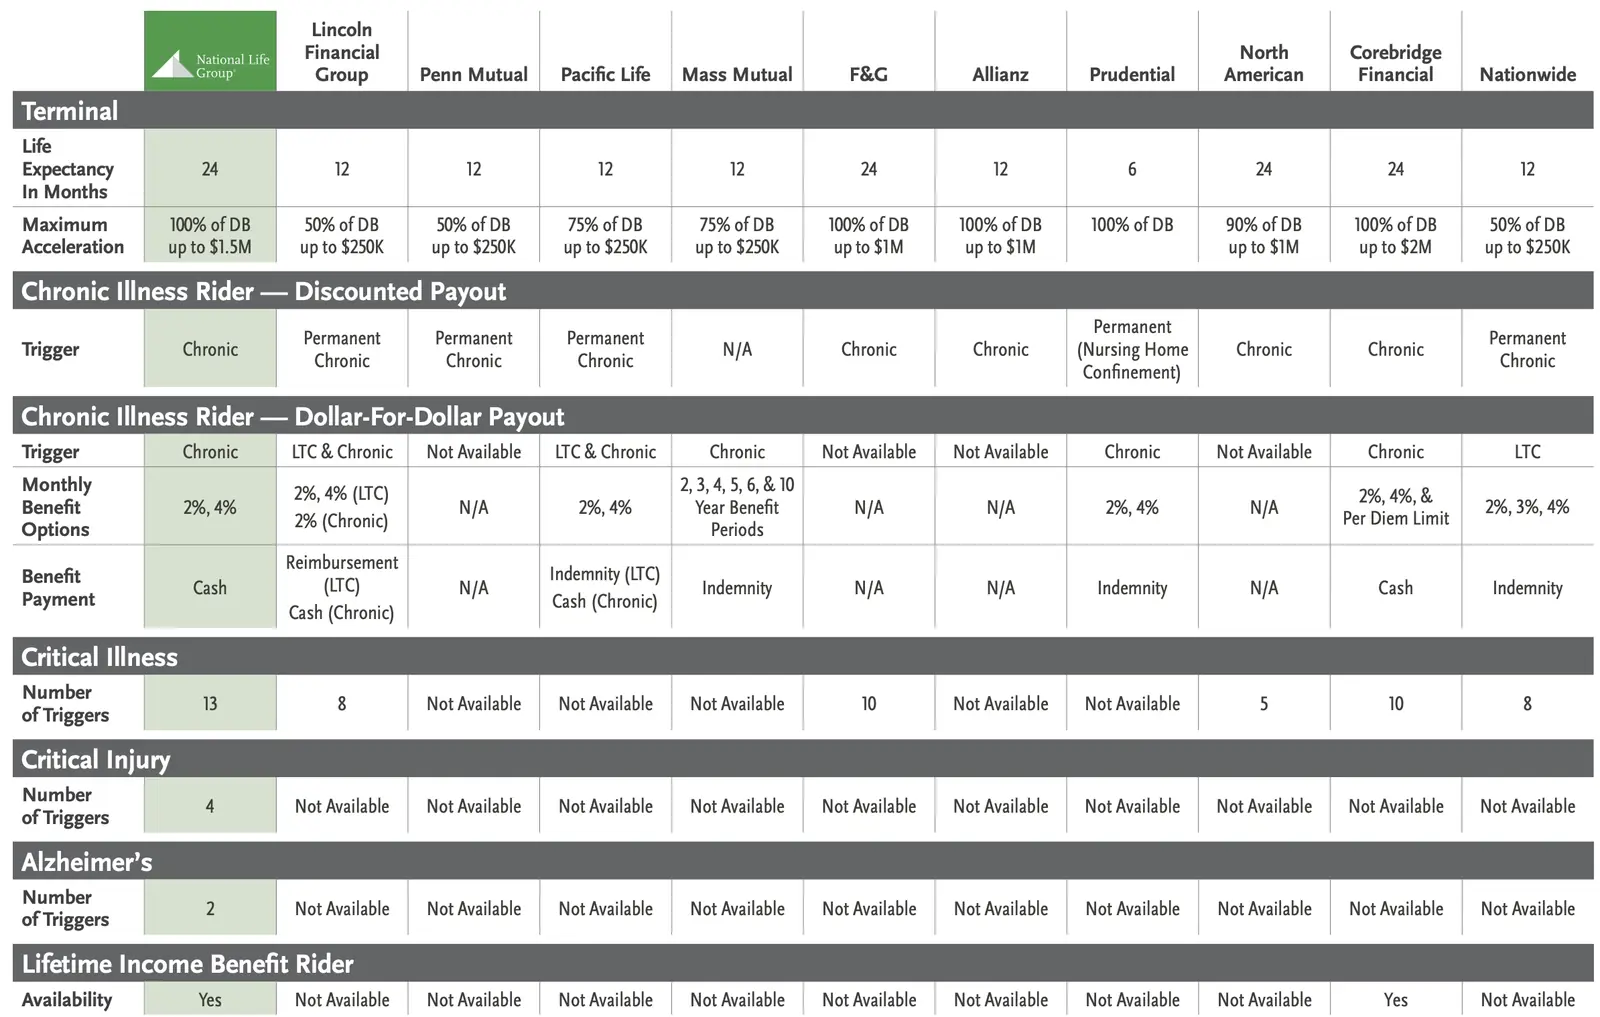
这张表是这一页最值钱的一块, 因为它比的是条款规格,不是感觉:月数、赔付比例、额度上限、触发项数, 每一项都能回到各家的产品资料去核对。
This table is the most valuable thing on this page, because it compares specifications rather than impressions: months, percentage of death benefit, caps, and trigger counts. Every cell can be checked against each carrier's own product literature.
| 末期疾病Terminal | 慢性疾病Chronic | 重疾CI | 重伤Injury | 阿兹海默Alz. | |
|---|---|---|---|---|---|
| LLD 2.0 | 24 个月,100% 保额,上限 $1.5M24 months, 100% of DB, to $1.5M | 上限 $1.5MTo $1.5M | 13 | 4 | 2 |
| Corebridge | 24 个月,100% 保额,上限 $2M24 months, 100% of DB, to $2M | 上限 $2MTo $2M | 7 | 3 | — |
| TransAmerica | 12 个月,100% 保额,上限 $1.5M12 months, 100% of DB, to $1.5M | 90% 保额,上限 $1.5M;18 岁以下不适用90% of DB to $1.5M; not available under 18 | 12 18 岁以下不适用12 not under 18 |
1 18 岁以下不适用1 not under 18 |
— |
| F&G | 24 个月,100% 保额,上限 $1M24 months, 100% of DB, to $1M | 上限 $1MTo $1M | 8 | 2 | — |
| Allianz | 12 个月,100% 保额,上限 $1M12 months, 100% of DB, to $1M | 上限 $1MTo $1M | — | — | — |
| Nationwide | 12 个月,50% 保额,上限 $250k12 months, 50% of DB, to $250k | 最多保额的 20%Up to 20% of DB | 8 每次最多 10% 保额或 $25K,最多 5 次8 up to 10% of DB or $25K per claim, 5 claims max | — | — |
| Pacific LifePacific Life | 12 个月,75% 保额,上限 $250k12 months, 75% of DB, to $250k | Permanent ChronicPermanent chronic | — | — | — |
读这张表要读对地方。LLD 强的不是每一格,是覆盖面: 重疾 13 项、重伤 4 项、阿兹海默 2 项,阿兹海默这一列,六家全是空的。 而末期与慢性的额度上限,Corebridge 的 $2M 比 LLD 的 $1.5M 高, 这一格要主动说,不要绕过去。
Read it in the right place. LLD's strength isn't every cell; it's the breadth: 13 critical illnesses, 4 injuries, and 2 Alzheimer's conditions, where the Alzheimer's column is empty for all six competitors. But on the terminal and chronic caps, Corebridge's $2M beats LLD's $1.5M. Volunteer that cell rather than walking around it.
Nationwide 那两格值得特别注意,因为它是最容易被误读的。 末期 12 个月、只赔 50% 保额、上限 $250,000;慢性最多 20% 保额。 换成数字:一张 $100 万的保单,Nationwide 的末期条款最多提前给 $250,000, LLD 是 $1,000,000(受 $1.5M 上限约束)。 但这不等于「Nationwide 的保单不好」,它可能在费用或指数策略上更有优势 (见下一节)。对客户只比生前福利这一项,是不诚实的比法。
The two Nationwide cells are the ones most often misread. Terminal at 12 months, 50% of the death benefit, capped at $250,000; chronic at up to 20% of the death benefit. In figures: on a $1M policy, Nationwide's terminal rider advances at most $250,000 where LLD advances $1,000,000, subject to the $1.5M cap. That does not make it a bad policy; it may well be stronger on charges or index strategy (next section). Comparing on living benefits alone is not an honest comparison.
TransAmerica 那三格「18 岁以下不适用」是这张表上最实用的一条。 给小孩做保单的时候,这一条直接决定了产品选择, 而它是一个规格差别,不是优劣判断,可以放心讲给客户听。
TransAmerica's three "not available under 18" cells are the most practically useful line on this table. On a juvenile case that single restriction decides the product, and it's a specification difference rather than a quality judgement, so it's safe to state to a client.
培训幻灯片里另有两张同业对照,补充几家上表没有的公司(资料日期以各家当期为准): New York Life 末期 12 个月、上限 $50 万,慢性要另付费买长期护理附约,没有重疾和重伤; American National 末期 24 个月,0–64 岁上限 $200 万、65 岁起 $100 万,慢性、重疾、重伤上限 $200 万但 65 岁起不适用; Lincoln、Penn Mutual、MassMutual 末期 12 个月、最多 50%–75% 保额、上限 $25 万,Prudential 末期 6 个月,North American 24 个月、90% 保额、上限 $100 万。 终身收入附约(LIBR)一行,十一家里只有国家人寿和 Corebridge 有。重疾项数的口径各家不同:有的把重伤算进重疾, 所以同一家在不同对照表里可能是「重疾 7 + 重伤 3」,也可能是「重疾 10」。
The training slides carry two more peer tables, adding carriers not in the table above (dates per each carrier's current material): New York Life: terminal at 12 months to $500K, chronic only through a separately priced LTC rider, no critical illness or injury; American National: terminal at 24 months, to $2M at ages 0–64 and $1M from 65; chronic, critical illness and injury to $2M but not from 65; Lincoln, Penn Mutual and MassMutual: terminal at 12 months, 50–75% of DB to $250K; Prudential terminal at 6 months; North American at 24 months, 90% of DB to $1M. On the lifetime income rider (LIBR) row, only National Life and Corebridge of the eleven offer one. Trigger counts are tallied differently: some carriers fold injuries into critical illness, so the same carrier can read "7 illnesses + 3 injuries" in one table and "10 critical illness" in another.
更多公司、更新日期的生前福利上限和 IUL 规格对照,见《同业横向对照》。
More carriers, with dated living-benefit limits and IUL specs, are in Carrier Comparisons.
七、LLD 不是每一项都赢7. Where LLD doesn't win
横向比 IUL,可以看六个维度:公司历史、生前福利、费用、 指数策略、贷款与退休、客户服务。逐项比下来,没有哪一家每项都赢。
IULs can be compared across six dimensions: company history, living benefits, charges, index strategy, loans and retirement, and customer service. Taken one at a time, no carrier wins them all.
这一节最该带走的,是 LLD 输在哪里:
What's worth taking away is where LLD doesn't win:
LLD 在生前福利这一项明显领先; 但在指数策略、贷款与退休、客户服务三项上, Allianz 都强过同表其他几家; 公司历史一项,Pacific Life 最突出; 费用一项,Nationwide 最有优势。
LLD leads clearly on living benefits. But on index strategy, loans and retirement, and customer service, Allianz is ahead of everyone else on the sheet; Pacific Life stands out on company history; and Nationwide is strongest on charges.
这件事应该让我们更好卖,不是更难卖。 一个能主动说出「这一项别人比我们强」的人,说「这一项我们强」的时候才有人信。 而且它也是真的:如果客户要的是最低费用或最灵活的贷款,LLD 未必是那个答案。 这正是我们代理多家公司的意义: 不是每个客户都该买同一张保单。
This should make us better at selling, not worse. Someone willing to say "they beat us on that" is believed when they say "we're stronger here." And it's simply true: if what a client needs is the lowest charges or the most flexible loan, LLD may not be the answer. Which is the point of representing more than one carrier: not every client should end up with the same policy.
六家公司的出身,一句话一家Where each carrier came from
| 国家人寿 NLGNational Life | 1848 年,佛蒙特州蒙彼利埃。最早做 IUL 的公司1848, Montpelier, Vermont. The oldest IUL carrier |
| Pacific Life | 1868 年,Newport1868, Newport |
| Allianz | 1890 年,德国1890, Germany |
| TransAmerica | 1904 年,旧金山;1999 年被 Aegon 收购1904, San Francisco; acquired by Aegon in 1999 |
| Corebridge | 前身是 AIG 人寿与退休业务。AIG 1919 年创立于上海(初名 American Asiatic Underwriters,1967 年更名 AIG);2008 年金融危机中接受约 $1,820 亿救助;2022 年该部门更名 Corebridge 并 IPO 分拆Formerly AIG's Life & Retirement division. AIG was founded in 1919 in Shanghai as American Asiatic Underwriters, renamed AIG in 1967; took roughly $182 billion of support in the 2008 crisis; the division was rebranded Corebridge and spun off by IPO in 2022 |
| Nationwide | 1926 年,俄亥俄州;从车险到财产意外险再到寿险1926, Ohio; from auto to P&C to life |
| F&G | 1959 年,爱荷华州,同表里最年轻的一家1959, Iowa; the youngest on the sheet |
2008 年那笔救助可以讲事实,不要讲成结论。 「AIG 被救过,所以不安全」是一句站不住的话: 救助发生在 2008 年,Corebridge 是 2022 年分拆出来的独立上市公司, 而且那笔钱早已偿还。把历史事实讲清楚是专业, 拿它暗示今天的偿付能力就是保单替换那一页 讲的那种不合规的比法。公司的财务强度看当期评级,不看十八年前的新闻。
The 2008 support is a fact you can state; it is not a conclusion. "AIG was bailed out, so it isn't safe" doesn't hold: that was 2008, Corebridge was spun off as a separate public company in 2022, and the support was repaid long ago. Stating the history accurately is professional; using it to imply something about today's claims-paying ability is the kind of comparison Policy Replacement warns about. Financial strength is read from current ratings, not from eighteen-year-old headlines.
八、用这张对照表的四条规矩8. Four rules for using this comparison
- 核对当期产品资料再用。这张对照表成稿于 2026 年 5 月, 条款规格、额度上限与触发项数每家都会改。 拿一张过期的对照表去跟客户比,出错的是你。
- Check the current product literature first. This table dates from May 2026, and rider specs, caps, and trigger counts change at every carrier. A stale comparison table used in front of a client is your error, not theirs.
- 只比规格,不比好坏。表里每一格都能回到对方的产品资料去核对; 「他们家不行」不能核对。前者是专业,后者是 保单替换那一页列的红线。
- Compare specifications, not quality. Every cell here can be verified against the other carrier's own literature; "their product is bad" cannot be. The first is professional; the second is on the red-line list in Policy Replacement.
- 输的那几格要自己先说。Corebridge 的末期与慢性上限比我们高, Allianz 在指数策略与贷款上更强,Nationwide 的费用更低。 主动说出来,比被客户查出来好一百倍。而且这三句话正好说明 你是在做规划,不是在推一张保单。
- Volunteer the cells you lose. Corebridge's terminal and chronic caps are higher, Allianz is stronger on index strategy and loans, Nationwide's charges are lower. Saying it yourself beats a client finding it by an enormous margin, and those three sentences are what demonstrate you're planning rather than pushing a policy.
- 不要把生前福利当成唯一的比较维度。 客户要的如果是最低成本的身故保障,或者最灵活的退休贷款, 这张表根本不是该拿出来的那一张。先问需求,再选表。
- Don't treat living benefits as the only axis. If what the client needs is the cheapest death benefit or the most flexible retirement loan, this isn't the table to reach for. Establish the need first, then pick the comparison.
九、核保:LLD 和别的产品不一样的几条9. Underwriting: where LLD differs
按 2026 年 1 月版《Life Insurance Underwriting Guide》。完整流程、体检矩阵和不可保清单见核保那一页。
From the January 2026 Life Insurance Underwriting Guide. The full process, requirement matrix and uninsurable list are on the Underwriting page.
- 年龄和面额:Standard NT 从 0 岁起签,Elite 18–75 岁,其他等级到 85 岁;最低面额 $50K(SummitLife 最低 $1M)。
- Ages and face: Standard NT issues from age 0, Elite at 18–75, the other classes to 85; the minimum face is $50K (SummitLife's is $1M).
- 体检:$250K 以下到 65 岁都只要申请,66–69 岁要体检加验血验尿,70 岁以上所有面额都要 ME/APS。
- Exams: up to $250K, application only through age 65; exam, blood and urine at 66–69; ME/APS at every amount from 70.
- EZ 免体检:18–50 岁 $3M、51–60 岁 $1M、61–65 岁 $250K 以内;过去 12 个月做过常规体检的,18–50 岁可到 $5M,51–60 岁可到 $3M。
- EZ, no exam: to $3M at 18–50, $1M at 51–60, $250K at 61–65; with a routine physical in the past 12 months, to $5M at 18–50 and $3M at 51–60.
- Express 等级到 $3M:LLD 总保额 $3M 以内都能用 Express 等级,国家人寿其他永久型只到 $2M。评级偏高的客户,这一条常常决定用哪个产品。
- Express classes to $3M: LLD allows the Express classes up to $3M total face, where National Life's other permanent products stop at $2M. For a client who rates high, this often decides the product.
- Express Standard NT 2(225%–300%)没有生前福利,也没有 LIBR。客户落到这一档,LLD 最大的卖点就没了,出单前要讲清楚。
- Express Standard NT 2 (225–300%) carries no living benefits and no LIBR. A client who lands there loses LLD's main selling point; say so before issue.
- 未成年人吸烟:0–17 岁已知吸烟的,按 Express Standard NT 1 签发。
- Juvenile smokers: known smokers aged 0–17 are issued in Express Standard NT 1.
本文仅供一般性财务教育使用,不构成保险、税务或投资建议;文中数字为说明性举例,具体保障与条款以保单为准。
General financial education only; not insurance, tax, or investment advice. Figures are illustrative; the policy governs.