- 一条时间线The timeline
- 定期寿险 Term LifeTerm Life
- 终身寿险 Whole LifeWhole Life
- 万能寿险 Universal LifeUniversal Life
- 投资型万能寿险 VULVariable Universal Life
- 指数型万能寿险 IULIndexed Universal Life
- 封顶与保底:举个例子Cap and floor: an example
- IUL 的潜在问题Where IUL can go wrong
- 再说税Taxes
- 后来加上的生前福利Living benefits, added later
- 问自己三个问题Three questions to ask yourself
人寿保险先分两大类。一类是消费型:保一段时间,到期就没了, 保费一般不退。另一类是永久型:保一辈子,里面还有一个存钱的账户, 叫现金价值(cash value)。五代产品,就是在四件事上来回取舍: 灵不灵活、成本清不清楚、回报高不高、风险大不大。
Life insurance splits into two families. Term covers you for a set period, then ends, and the premiums generally aren't returned. Permanent covers you for life and carries a savings account inside it, called cash value. The five generations are a series of trade-offs across four questions: how flexible is it, how clear are the costs, how high is the return, and how big is the risk?
一、一条时间线1. The timeline
定期寿险 Term Life
Term Life
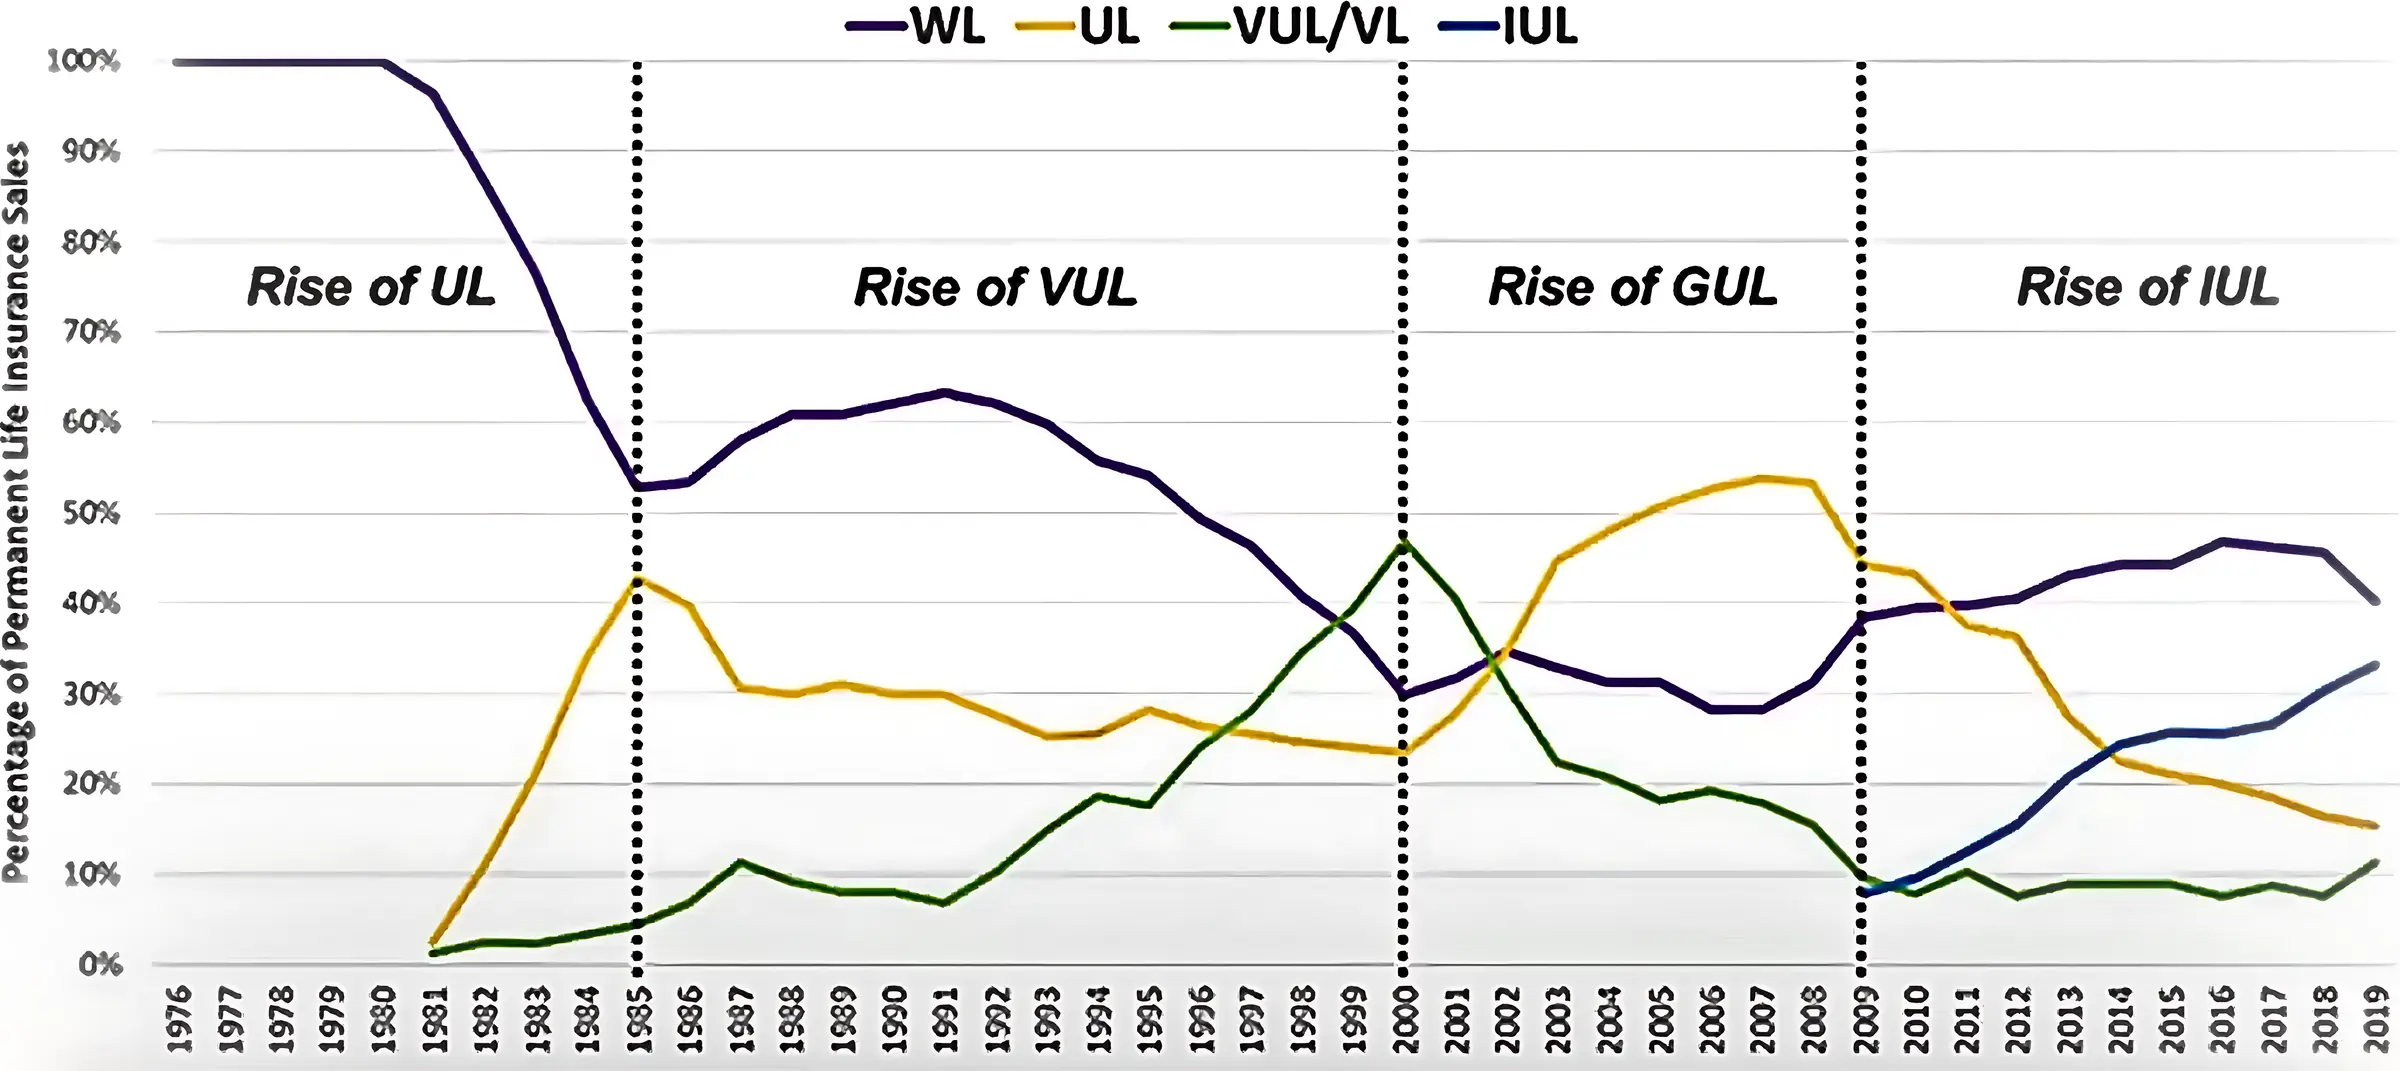
1583 年的伦敦就已经有一年期的寿险保单。纯保障。便宜,但到期即止,没有现金价值。
London already had one-year life policies in 1583. Pure protection. Cheap, but it expires, and there's no cash value.
终身寿险 Whole Life
Whole Life
1762 年成立的伦敦 Equitable 开始卖平准保费的终身寿险;美国在 1840–50 年代普及, 纽约人寿(1845)、万通(1851)都是那时成立的。解决了"保不到终身"的问题, 但保费与保额都不灵活,成本高。
The Equitable, founded in London in 1762, began selling level-premium whole life; in the US it spread in the 1840s–50s, when New York Life (1845) and MassMutual (1851) were founded. Solved the expiry problem, but premium and face amount are locked, and it's expensive.
万能寿险 Universal Life
Universal Life
解决了"不灵活"和"不透明",但按保险公司每年宣布的利率计息,利率不保证,也没有别的策略可选。
Solved flexibility and transparency, but interest is credited at a rate the carrier declares each year, with no guarantee and no other strategy to choose.
投资型万能寿险 VUL
Variable Universal Life
解决了"回报低",钱真的放进市场,客户自选股票、债券子账户,代价是完全不保底。
Solved low returns by putting the money in the market through sub-accounts you pick, at the cost of having no floor at all.
指数型万能寿险 IUL
Indexed Universal Life
解决了"没有保底",按指数涨幅记息,涨有封顶、跌有保底。
Solved the no-floor problem: interest follows an index, capped on the upside, floored on the downside.
带生前福利的 IUL
IUL with living benefits
2007 年起,生前福利条款被系统性地加进 IUL。国家人寿这条产品线依次是 Living Life(2016)、Living Life By Design(2019)、Living Life Defender(2023)、 Living Life Defender 2.0(2025)。
From 2007, living benefit riders were built into IUL systematically. National Life's line runs Living Life (2016), Living Life By Design (2019), Living Life Defender (2023), and Living Life Defender 2.0 (2025).
二、第一代:定期寿险 Term Life2. Generation one: Term Life
定期寿险是最老的一种,四百多年前就有了。它有点像车险:保 10 年、20 年、30 年, 这期间人走了,家人拿到保额;平安到期,保费一般不退。好处是便宜。年轻健康时买,价格很低, 还能锁住你现在的健康等级。
Term is the oldest kind, more than four hundred years old. It works a bit like car insurance: you're covered for 10, 20 or 30 years; if you die in that window your family receives the face amount, and if you reach the end safely, the premiums generally aren't returned. The upside is price. Bought young and healthy, it's very cheap, and it locks in your current health rating.
麻烦是在到期以后。想接着保,一般有两条路:一条是按合同续保, 不用重新体检,但价格按年龄重算,会大幅上涨;另一条是重新买一张, 要重新审核健康,不一定批得下来。
The trouble starts when it expires. To stay covered there are usually two routes: renew under the contract, with no new medical exam but a price recalculated for your age, which jumps sharply; or buy a new policy, which means new underwriting that may not be approved.
优点Pros
- 年轻且健康时价格非常便宜
- Very cheap while you're young and healthy
- 可以锁定当前的健康等级
- Locks in your current health classification
缺点Cons
- 只保一段时间:10 / 15 / 20 / 30 年
- Temporary only: 10 / 15 / 20 / 30 years
- 不存钱,类似车险,平安到期保费一般不退
- No accumulation: like car insurance, premiums generally aren't returned
- 到期按合同续保价格大幅上涨;重新买要重新核保,不一定批
- Contract renewal costs far more; a new policy needs new underwriting and may be declined
| 方案Option | 缴费Payments | 合计Total |
|---|---|---|
| 30 年定期寿险 36–66 岁30-year term ages 36–66 |
$1,500 × 30 | $45,000 |
| 按合同续保 20 年 66–86 岁 价格按年龄重算,取平均Renew 20 years under contract ages 66–86 repriced for age, averaged |
$15,000 × 20 | $300,000 |
| 合计(保到 86 岁,一分钱没存下)Total (covered to 86, nothing saved) | $345,000 | |
| 指数型万能险 IUL 36–120 岁IUL ages 36–120 |
$9,600 × 15 | $144,000 |
同一个人买 IUL,一年 $9,600,交 15 年,一共 $144,000。 保费先扣掉费用和保险成本,剩下的留在保单里延税增长。按计划书演示,65 岁的时候, 现金价值大约 $35 万(演示值,非保证)。定期寿险那 $345,000 则是花掉的。
The same person buying IUL pays $9,600 a year for 15 years, $144,000 in all. Fees and the cost of insurance come out first, and what's left stays in the policy and grows tax-deferred. On the illustration, cash value at 65 is roughly $350,000 (illustrated, not guaranteed). The term column's $345,000 is simply spent.
这不意味着定期寿险是坏产品。定期寿险适合谁?如果一个人刚背上 $80 万房贷, 孩子才两岁,预算又紧,先用定期险把缺口补上,是完全正确的决定。问题只在于: 把它当成终身方案,数学上不成立。
None of this makes term a bad product. Who is it for? Someone who just took on an $800k mortgage, with a two-year-old at home and a tight budget: covering that gap with term first is exactly the right call. The problem is only this: as a lifetime plan, the math doesn't work.
三、第二代:终身寿险 Whole Life3. Generation two: Whole Life
终身寿险也有两百多年的历史了。它弥补了定期险到期会失效这个缺点:只要按时交钱, 就可以保一辈子。保额和现金价值的增长(大约 3–4%)都写在合同里保证。 有些公司每年还会分红,但分红是不保证的。
Whole life is more than two hundred years old. It fixes term's expiry problem: pay on time and you're covered for life. Both the face amount and cash value growth (roughly 3–4%) are guaranteed in the contract. Some carriers also pay an annual dividend, but dividends aren't guaranteed.
但代价有三个。第一,贵。同样 36 岁、$100 万,一年大约 $22,000, 15 年付清,一共 $330,000 的保费,是刚才 IUL($144,000)的两倍多。 第二,不灵活,保单生效以后,保费和保额基本改不了。 第三,不透明,里面每一项成本扣了多少,你看不到。
The price comes in three parts. First, it's expensive. Same 36-year-old, same $1M: about $22,000 a year, paid up in 15 years, $330,000 in total, more than twice the IUL's $144,000. Second, it's rigid: once issued, premium and face amount are essentially fixed. Third, it's opaque: you can't see what each cost deducts.
优点Pros
- 保障可以做到终身,解决了 Term 到期的问题
- Lifetime coverage, which fixes term's expiry problem
- 按时缴费,保额和约 3–4% 的增长由合同保证
- Paid on schedule, the face amount and roughly 3–4% growth are contractually guaranteed
- 部分公司有分红(不保证)
- Some carriers pay dividends (not guaranteed)
缺点Cons
- 保费高昂:$22,000/年 × 15 年 = $330,000
- Expensive: $22,000/year × 15 years = $330,000
- 保费与保额不灵活,保单生效后基本不可改变
- Premium and face amount are fixed once issued
- 保单成本不透明,投资策略不可选
- Costs aren't itemized, and there's no strategy choice
- 保单贷款利率高,通常 5–6% 固定
- Policy loan rates are high, typically 5–6% fixed
代表公司:New York Life 纽约人寿、Mass Mutual 万通人寿、MetLife 大都会、 Northwestern Mutual 西北互惠。
Typical carriers: New York Life, MassMutual, MetLife, Northwestern Mutual.
四、第三代:万能寿险 Universal Life4. Generation three: Universal Life
万能寿险 1979 年诞生,补上了终身寿险的两个缺点。一个是灵活: 保费可以多交少交,根据自己的情况而定,保额也可以调整。另一个是透明: 每个月扣多少保险成本、多少费用,对账单上一项一项列着,非常清楚。
Universal life arrived in 1979 and fixed two of whole life's flaws. One is flexibility: you can pay more or less depending on your situation, and the face amount can be adjusted. The other is transparency: each month's cost of insurance and fees are itemized on the statement, line by line.
它按保险公司每年宣布的利率计息,大约 5% 左右,但这个利率不保证, 你也没有别的策略可以选。新的风险也随之而来:连着几年交得太少,现金价值不够扣成本, 保单就会失效。
Interest is credited at a rate the carrier declares each year, around 5%, but that rate isn't guaranteed and there's no other strategy to choose. And a new risk arrives with it: underfund for several years in a row, and when cash value can't cover the charges, the policy lapses.
优点Pros
- 保费与保额灵活,解决了 Whole Life 不灵活的缺点
- Flexible premium and face amount, which fixes whole life's rigidity
- 保单成本逐项列在对账单上,解决了不透明的缺点
- Costs are itemized on the statement
缺点Cons
- 按保险公司宣布的利率计息,约 5%,不保证
- Credited at a carrier-declared rate, around 5%, not guaranteed
- 投资策略不可选
- No strategy choice
- 贷款利率高,5–6% 固定
- Loan rates of 5–6% fixed
- 连续几年交得太少,保单会失效
- Several years of underfunding can lapse the policy
- 保费仍然较高:$12,000/年 × 15 年 = $180,000
- Still expensive: $12,000/year × 15 years = $180,000
五、第四代:投资型万能寿险 VUL5. Generation four: Variable Universal Life
VUL 也可以叫投连险,是八十年代中期出来的产品。它想弥补的是终身寿险和万能寿险回报低的问题。 保单里的钱,你可以自己挑子账户,股票的、债券的都有,钱是真的放进了市场。 涨的时候没有上限,跌的时候也没有保底。
VUL, sometimes called a variable or investment-linked policy, appeared in the mid-1980s to fix the low returns of whole life and universal life. You pick the sub-accounts, equity or bond, and the money really does go into the market. No ceiling on the way up, and no floor on the way down.
优点Pros
- 保费与保额灵活
- Flexible premium and face amount
- 回报潜力高,涨的时候没有上限
- Higher return potential, with no ceiling
- 客户可自选子账户:股票、债券等
- You choose the sub-accounts: equity, bond, and so on
缺点Cons
- 风险高,完全不保底
- High risk, no floor at all
- 投资下跌、现金价值缩水时,保险成本照扣,钱不够扣保单就可能失效
- When investments fall, charges keep coming out, and the policy can lapse
- 可能需要支付投资管理费用
- May carry investment management fees
- 贷款利率 5–6% 固定
- Loan rates 5–6% fixed
VUL 的问题出在风险与保障目的不匹配,不在回报。 如果选择的投资下跌,现金价值缩水,保险成本还是每个月照样扣。钱不够扣,保单可能就失效了。 所以你最需要这张保单的时候,可能正好是它撑不住的时候。
VUL's problem is a mismatch between risk and purpose, not returns. If your investments fall and cash value shrinks, the cost of insurance still comes out every month. When there isn't enough to cover it, the policy can lapse. The moment you most need the policy may be exactly the moment it can't hold.
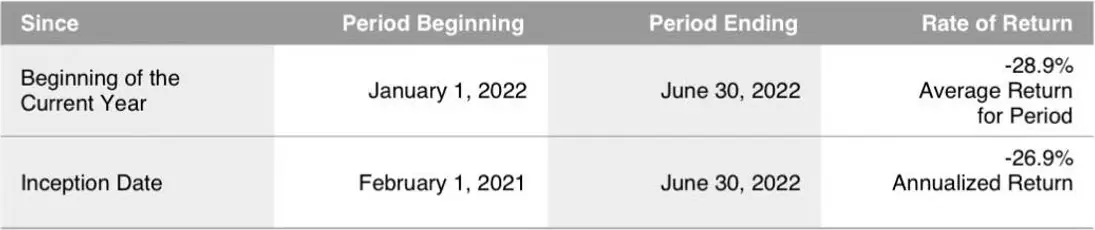
举一个真实的例子:一张 VUL 保单的对账单上,2022 年 1 月 1 日到 6 月 30 日的回报是 −28.9%; 从 2021 年 2 月 1 日生效算起,到 2022 年 6 月 30 日,年化回报 −26.9%。那半年标普 500 大约跌了两成, 这个账户跌得更多。这只是一个账户在一个坏年份的结果,但它就是"不保底"的样子。
A real example: one VUL statement shows −28.9% from 1 January to 30 June 2022, and −26.9% annualised from inception on 1 February 2021 to 30 June 2022. The S&P 500 fell roughly a fifth over that half-year, and this account fell further. It's one account in one bad year, but that is what "no floor" looks like.
六、第五代:指数型万能寿险 IUL6. Generation five: Indexed Universal Life
IUL 在 1997 年第一次被提出,它要解决的,就是 VUL 没有保底的问题。 IUL 的钱不直接进股市。保险公司看一个指数,最常见的是标普 500, 按它一年涨了多少,给你记利息。规则就两条:
IUL was first introduced in 1997 to solve VUL's missing floor. In an IUL the money doesn't go directly into the stock market. The carrier watches an index, most often the S&P 500, and credits you interest based on how much it rose that year. There are just two rules:
- 保底,也是最重要的一点:指数跌了,这一年一般记零,不会让利息记为负数。
- The floor, the most important part: if the index falls, that year is generally credited zero. Interest is never credited as a negative.
- 封顶:指数涨得再多,你最多记到一个上限。
- The cap: however much the index rises, you're credited up to a ceiling.
机制细节见 IUL 如何运作。
The mechanics are covered in How IUL Works.
优点Pros
- 保费与保额灵活
- Flexible premium and face amount
- 按标普 500 等指数记息,钱不直接进股市
- Credited against an index such as the S&P 500, without the money entering the market
- 指数下跌时一般记零,不亏,解决了 VUL 不保底的问题
- Generally zero, not a loss, in down years, which fixes VUL's missing floor
- 多种贷款方式:浮动利息贷款、无息贷款等
- Multiple loan types, including variable and wash loans
- 同样保额,所需保费通常低于其他永久型寿险(以演示为准)
- For the same face, usually less premium than other permanent products (per illustration)
需要知道的两点Two things to know
- 上涨有封顶,基础约 11%;国家人寿 LLD 的 Enhancer 条款任何保额都可开启,上限最高约 17%; 它的 Guaranteed Flex Rider 在满足缴费条件时,保证期内保单不会失效
- Upside is capped, around 11% at base; National Life LLD's Enhancer riders can lift the ceiling to about 17% at any face amount, and its Guaranteed Flex Rider keeps the policy in force during the guarantee period if its funding conditions are met
- 保费交得太少或借得太多,保单可能失效(见下文)
- Too little premium or too much borrowing can lapse the policy (see below)
同样 $100 万保额,总保费差多少Same $1M face: total premium compared
| 男 40 岁 · 标准体 · $100 万Male 40 · standard · $1M | 年保费 × 年限Annual × years | 总保费Total premium | 保额 ÷ 总保费Face ÷ total |
|---|---|---|---|
| NLG Living Life Defender (IUL) | $11,972 × 15 | $179,580 | 5.57 |
| New York Life | $28,230 × 20 | $564,600 | 1.77 |
| MassMutual | $23,520 × 20 | $470,400 | 2.13 |
| Penn Mutual | $20,300 × 20 | $406,000 | 2.46 |
| NLG Total Secure | $19,522 × 20 | $390,440 | 2.56 |
演示值,男 40 岁标准体,换年龄体况结果不同。
Illustrated values, male 40, standard class; results differ by age and health.
在这一份演示里,IUL 每 $1 总保费对应约 $5.57 的保额,终身寿险一类约 $1.8–2.6。 这个倍数只属于这一份演示:换一个人、换年龄、换体况、换缴费年限,数字都不一样, 要按客户自己的情况跑一份演示表来看。而且两边买到的东西不完全一样:终身寿险的保额由合同保证, IUL 能不能用 15 年的保费撑到老,要看将来实际的记息和成本。 IUL 常见的公司有 National Life Group 国家人寿、Corebridge(原 AIG)、TransAmerica、Allianz、 Nationwide、Pacific Life 太平洋人寿。
In this illustration, each $1 of total premium supports about $5.57 of IUL cover, against about $1.80–2.60 for the whole-life rows. That multiple belongs to this one illustration: change the person, the age, the health class or the payment period and every number changes, so run an illustration on the client's own facts. Nor are the two sides buying exactly the same thing: whole life's face amount is contractually guaranteed, while whether 15 years of IUL premium carries the policy into old age depends on future crediting and charges. Carriers common in IUL: National Life Group, Corebridge (formerly AIG), Transamerica, Allianz, Nationwide, Pacific Life.
市场怎么选How the market has chosen
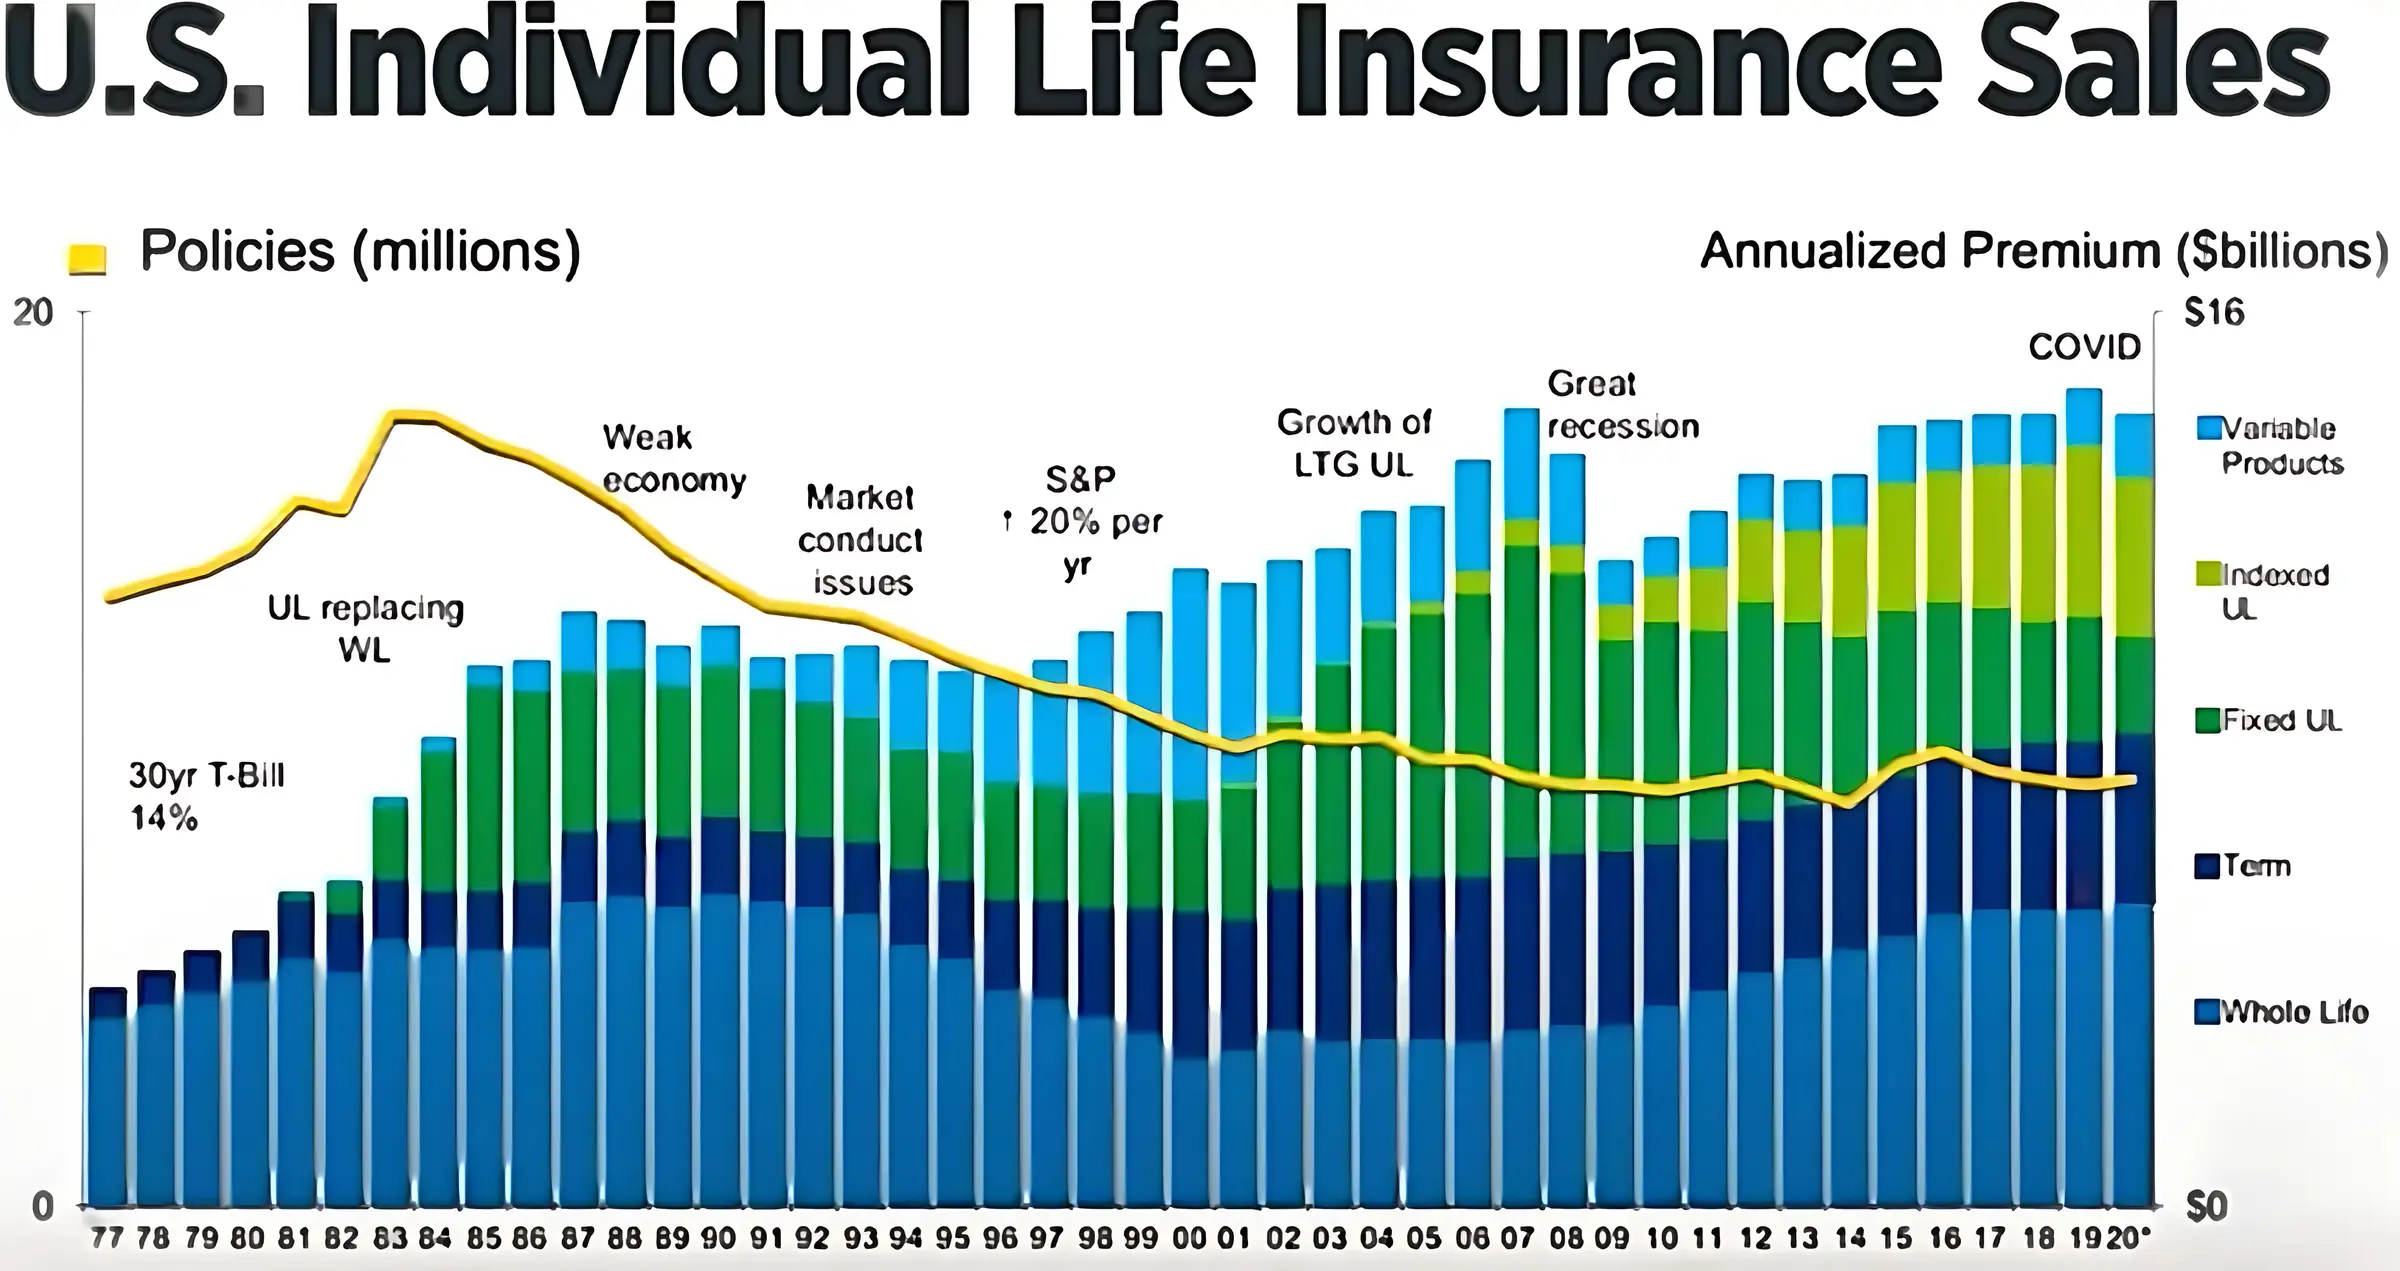
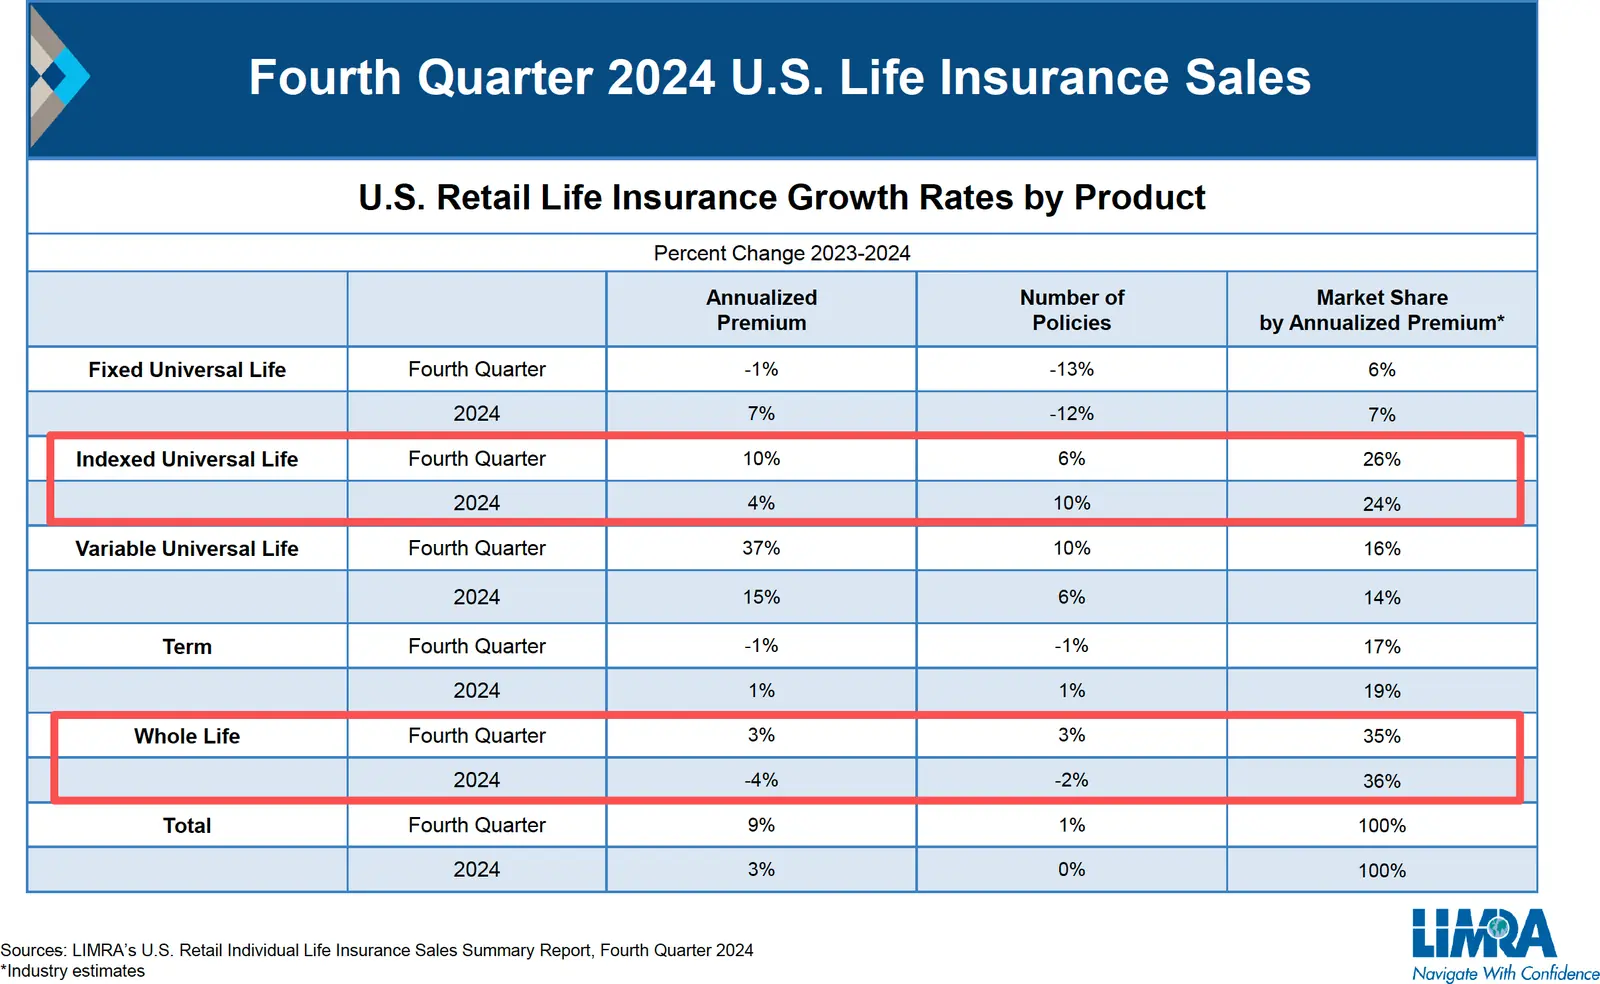
按 LIMRA 2024 年第四季度的零售个人寿险销售报告,2024 全年按年化保费算,终身寿险占 36%, 仍是最大的一类;IUL 占 24%,年化保费增长 4%、保单件数增长 10%;定期寿险 19%,投资型万能 14%, 固定万能 7%。投资型万能全年保费增长 15%,跟 2024 年股市走强有关。
Per LIMRA's retail individual life sales report for Q4 2024, by annualised premium for full-year 2024 whole life held 36%, still the largest category; IUL held 24%, with premium up 4% and policy count up 10%; term 19%, VUL 14% and fixed UL 7%. VUL premium rose 15% for the year, tied to 2024's strong market.
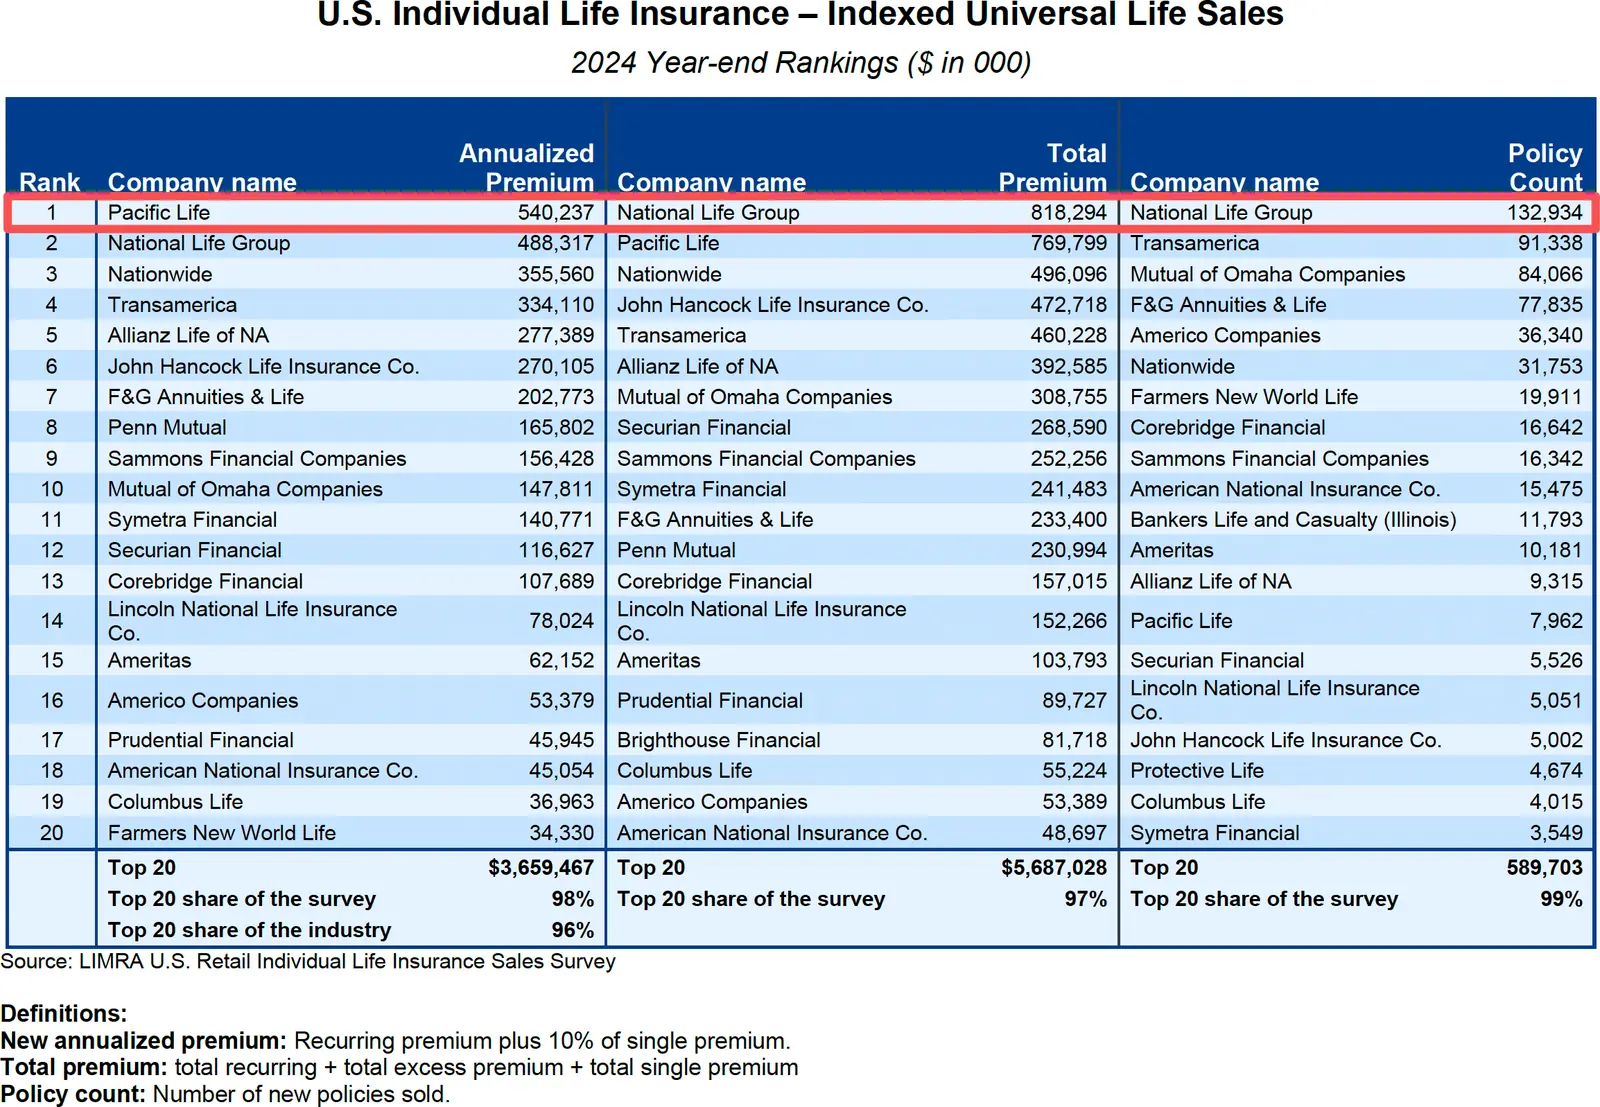
LIMRA 2024 年全年的 IUL 销售排名有三种口径:按新年化保费,Pacific Life 第一(约 $5.40 亿)、 国家人寿第二(约 $4.88 亿);按总保费,国家人寿第一(约 $8.18 亿);按保单件数,国家人寿第一(132,934 张)。 说"第一"时把口径和来源一起说出来。
LIMRA's full-year 2024 IUL rankings use three measures. By new annualised premium, Pacific Life is first (about $540M) and National Life second (about $488M); by total premium, National Life is first (about $818M); by policy count, National Life is first (132,934 policies). Whenever you say "first," give the measure and the source.
七、封顶与保底:举个例子7. Cap and floor: an example
假设封顶是 11%。标普今年涨 20%,你记 11%;明年跌 20%,你记零。
Say the cap is 11%. The S&P gains 20% this year: you're credited 11%. Next year it falls 20%: you're credited zero.
长期平均下来能记多少?2021 年,有位投资顾问做过回测,用 1990 到 2021 年的标普 500 数据, 按封顶 11%、保底 0 计算,平均每年大约记 7%。回测用的是历史数据,不代表未来; 实际封顶会随保险公司调整,以保单为准。
What does that average out to over time? In 2021 an investment adviser ran a backtest on S&P 500 data from 1990 to 2021 with an 11% cap and a 0% floor, and the average credit came to about 7% a year. A backtest uses past data and doesn't predict the future; actual caps change at the carrier's discretion, and the policy governs.
八、IUL 的潜在问题8. Where IUL can go wrong
如果连续几年保费交得太少,又或者从保单借得太多,保单可能会失效。 所以专业的保单设计,和后续合理的保单维护,是很重要的。 断保的两种典型情形,见 IUL 如何运作。
Several years of too little premium, or too much borrowed from the policy, can cause it to lapse. That's why professional design up front, and sensible maintenance afterwards, matter so much. The two typical ways a policy lapses are covered in How IUL Works.
九、再说税9. Taxes
现金价值增长时先不交税;从保单里贷款拿钱,也不用交税。前提是两条: 保单一直有效,以及交的钱不超过税法的上限(否则会变成 MEC, 税务待遇完全不同)。详见 IUL 如何运作。
Cash value isn't taxed as it grows, and money taken out as a policy loan isn't taxed either. Two conditions apply: the policy stays in force, and funding stays under the tax code's limit (otherwise it becomes a MEC, with entirely different tax treatment). See How IUL Works.
十、后来加上的生前福利10. Living benefits, added later
后来,IUL 上又多了生前福利。有些保单可以加提前理赔重病的附加条款: 如果得了合同写明的重病,可以把保额提前理赔出来。能领多少,要根据疾病严重程度和条款等方面具体分析。 详见生前福利一文。
Later, IUL gained living benefits. Some policies can add an accelerated benefit rider for serious illness: if you're diagnosed with a condition named in the contract, part of the face amount can be paid out early. How much depends on the severity of the condition and the terms of the rider. See Living Benefits.
十一、问自己三个问题11. Three questions to ask yourself
- 自己在重疾、护理等方面的保障做好了吗?
- Is your coverage for serious illness and long-term care in place?
- 你想要的保障,是一段时间,还是一辈子?
- Do you want coverage for a period of time, or for life?
- 你愿不愿意每年把这笔保费存下来,为未来的退休做好准备?
- Are you willing to set this premium aside every year to prepare for retirement?
哪一代适合你,要看你的保障想要多久,钱能不能长期存得住。
Which generation fits you depends on how long you want the coverage to last, and whether the money can stay put for the long haul.
本文仅供一般性财务教育使用,不构成保险、税务或投资建议;文中数字为说明性举例,具体保障与条款以保单为准。各州规则不同、法规逐年调整,采取行动前请咨询持证专业人士。
General financial education only, not insurance, tax, or investment advice. Figures are illustrative; the policy governs. Rules vary by state and change over time; consult a licensed professional before acting.