Home/产品中心Products/为什么选择国家人寿Why Choose National Life

承保公司 · 约 9 分钟Carrier · 9 min

为什么选择国家人寿 National Life Group

Why Choose National Life Group

选公司比选产品更难,因为产品能演示,公司只能靠时间证明。 这一篇讲清楚我们把它放在核心位置的四个理由。

Choosing a carrier is harder than choosing a product: a product can be illustrated, but a company can only be proven by time. Here are the four reasons we put this one at the center.

幻灯片 · 14 页 · 每页下方附详细讲解Slides · 14 pages · full presenter notes under each ↓ 跳到全文↓ Skip to the full article

为什么选择国家人寿Why Choose National Life Group

Presented by Team Rise

各位伙伴好,我们是 Team Rise。今天这一组只回答一个问题:我们为什么把国家人寿 National Life Group 放在核心位置。

Hello, everyone. We're Team Rise. This set answers one question: why we put National Life Group at the center of what we do.

客户问这个问题,往往不是在问产品,而是在问"这家公司靠不靠得住"。一张永久寿险保单要管五十年、七十年, 今年的上限比别家高一点,远没有"八十五岁时这家公司还在不在、还按不按约定理赔"重要。所以今天我们讲公司,不讲产品。

When a client asks this, they're rarely asking about a product. They're asking whether the company can be trusted. A permanent policy runs fifty or seventy years. A slightly higher cap this year matters far less than whether the company is still there, and still paying as agreed, when the client is eighty-five. So today is about the company, not the product.

顺序是这样的:先用两个比方讲清楚代理商和保险公司是什么关系,再看 PFA 和国家人寿之间的关系; 然后讲互惠公司和股份公司的区别;接着是第三方怎么看它:评级、Ward's 50、Forbes 和 Wink 的排名; 再看历年销售、生前福利三十年的发展、资产放在哪里;最后介绍两本写过国家人寿和 PFA 的书。

Here's the order. Two analogies first, to make clear how an agency and an insurer relate, then the relationship between PFA and National Life. Next, the difference between mutual and stock companies. Then how outsiders see it: ratings, Ward's 50, Forbes and the Wink rankings. After that, sales over the years, thirty years of living benefits and where the assets sit. We close with two books that were written about National Life and PFA.

每个数字都尽量标了年份和出处。讲的时候请把年份一起带上:排名和评级每年都会变,过期的数字说出去,就是不准确的话。

Every figure carries its year and source wherever we have one. Say the year when you quote it: rankings and ratings change every year, and an outdated number is an inaccurate statement.

互动设计Interaction

开场请大家在聊天框里回答:客户问"为什么是这家公司"时,你现在会怎么回答?讲完这一组,再回头看看自己的答案。

Open by asking everyone to answer in the chat: when a client asks "why this company?", what do you say today? At the end of the set, look back at those answers.

代理商和保险公司的关系How an Agency and an Insurer Relate

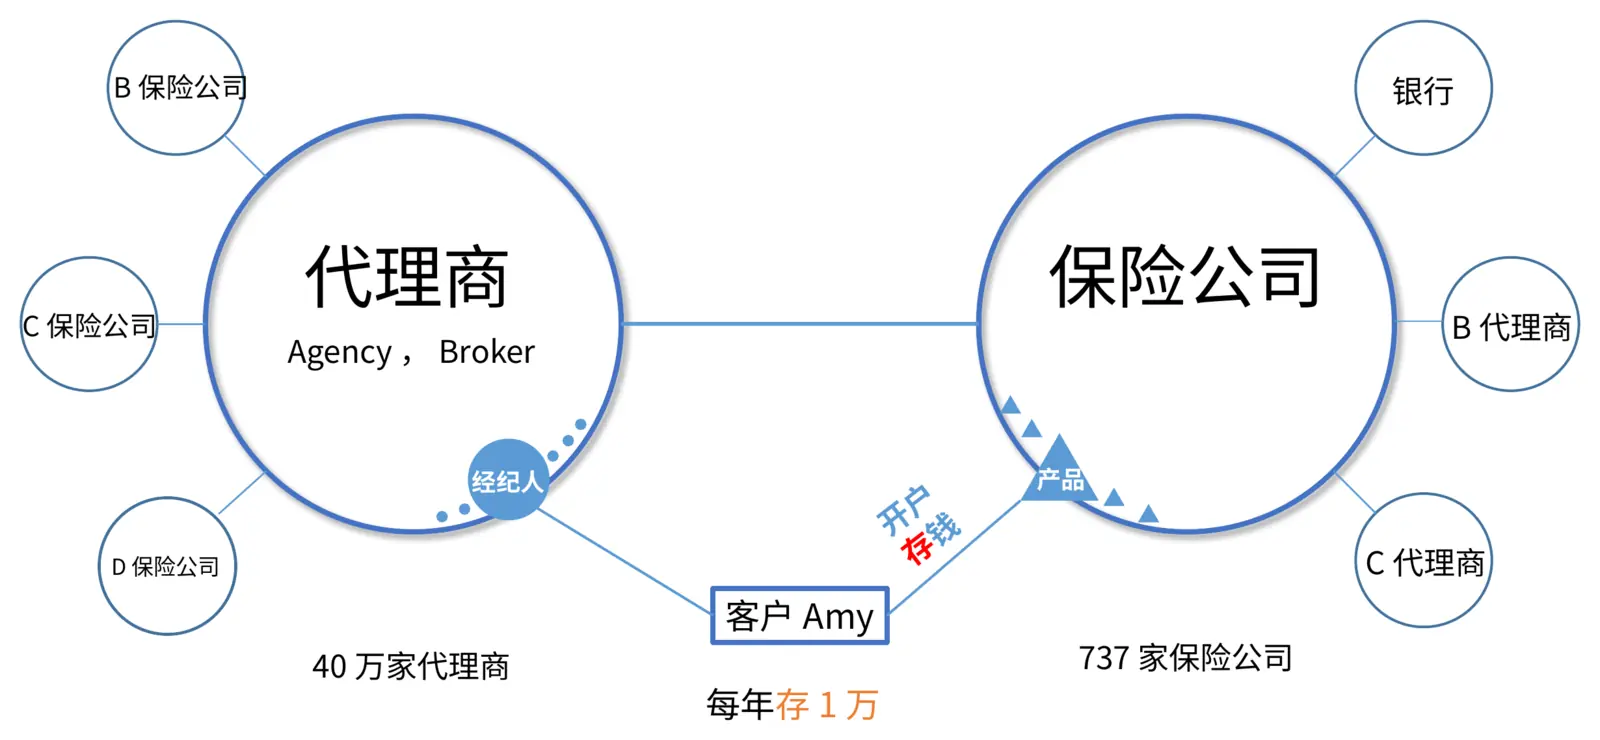
代理商和保险公司的关系示意图:代理商连着多家保险公司,保险公司连着多家代理商,经纪人在代理商、客户 Amy 开户存钱买保险公司的产品 / Diagram: an agency works with several insurers and an insurer with several agencies; the agent sits with the agency, and client Amy buys the insurer's product

很多客户,甚至很多新伙伴,第一次见面都会问:"你是哪家保险公司的?"这个问题背后有一个误会:以为经纪人就是保险公司的员工。这一页先把三个角色分清楚。

Many clients, and plenty of new partners, ask at the first meeting, "Which insurance company are you with?" Behind that question is a misunderstanding: that the agent is the insurer's employee. This slide separates the three roles.

左边是代理商,英文叫 Agency 或 Broker。代理商和很多家保险公司签约,经纪人挂在代理商名下, 替客户比较不同公司的产品,帮客户选一个合适的方案。

On the left is the agency, also called a broker. An agency is contracted with many insurers. Agents are appointed under the agency, compare products across companies for the client, and help the client choose a suitable plan.

右边是保险公司。产品是它设计的,核保是它做的,理赔也是它付的。一家保险公司不会只靠一个代理商卖产品, 它会同时通过很多家代理商、甚至银行来销售。全美一共有 719 家寿险公司,这是美国人寿保险协会 ACLI 2025 年的统计。

On the right is the insurer. It designs the product, it underwrites, and it pays the claims. An insurer doesn't rely on a single agency; it sells through many agencies at once, and through banks as well. There are 719 life insurers in the U.S., according to the American Council of Life Insurers (ACLI) for 2025.

中间是客户。举个例子,客户 Amy 每年缴 1 万美金保费。她通过经纪人认识了产品,但保单合同是和保险公司签的, 保费也是交到保险公司的账户里。这就像在银行开户:柜台帮你办手续,钱和账户都在银行那边。

In the middle is the client. Say a client, Amy, pays $10,000 a year in premium. She learned about the product through her agent, but her contract is with the insurer, and her premium goes into the insurer's account. It's like opening a bank account: the person at the counter does the paperwork, but the money and the account belong with the bank.

把这一点讲清楚,客户会放心很多:他的钱不在经纪人手里,也不在代理商手里,合同和理赔责任都在保险公司。 所以客户真正要看的,是保险公司本身靠不靠得住。这就是我们今天后面要讲的内容。

Make this clear and clients relax: their money isn't in the agent's hands or the agency's. The contract and the duty to pay claims sit with the insurer. So what the client really needs to judge is whether the insurer itself is sound, and that is what the rest of today covers.

合规提醒Compliance

讲这一页只讲角色关系。不要在客户或未入行的朋友面前拿某一笔保费去算经纪人能拿多少佣金,那属于收入展示。 保费也不要说成"存钱":寿险保费是买保障,现金值另有规则。

Keep this slide to the roles. Don't work out an agent's commission on a given premium in front of a client or someone not yet licensed; that is an earnings representation. And don't call premium "saving": premium buys cover, and cash value follows its own rules.

图是原稿截图:上面的「737 家保险公司」是较早的口径,讲的时候用 ACLI 2025 年的 719 家;「40 万家代理商」找不到出处,不要念。原稿底部的佣金金额已经去掉。

The image is the original slide. Its "737 insurers" is an older count; say 719 (ACLI 2025). "400,000 agencies" has no source we can find, so leave it out. The commission figures at the bottom of the original have been removed.

换个比方:超市和供货商Another Analogy: Stores and Suppliers

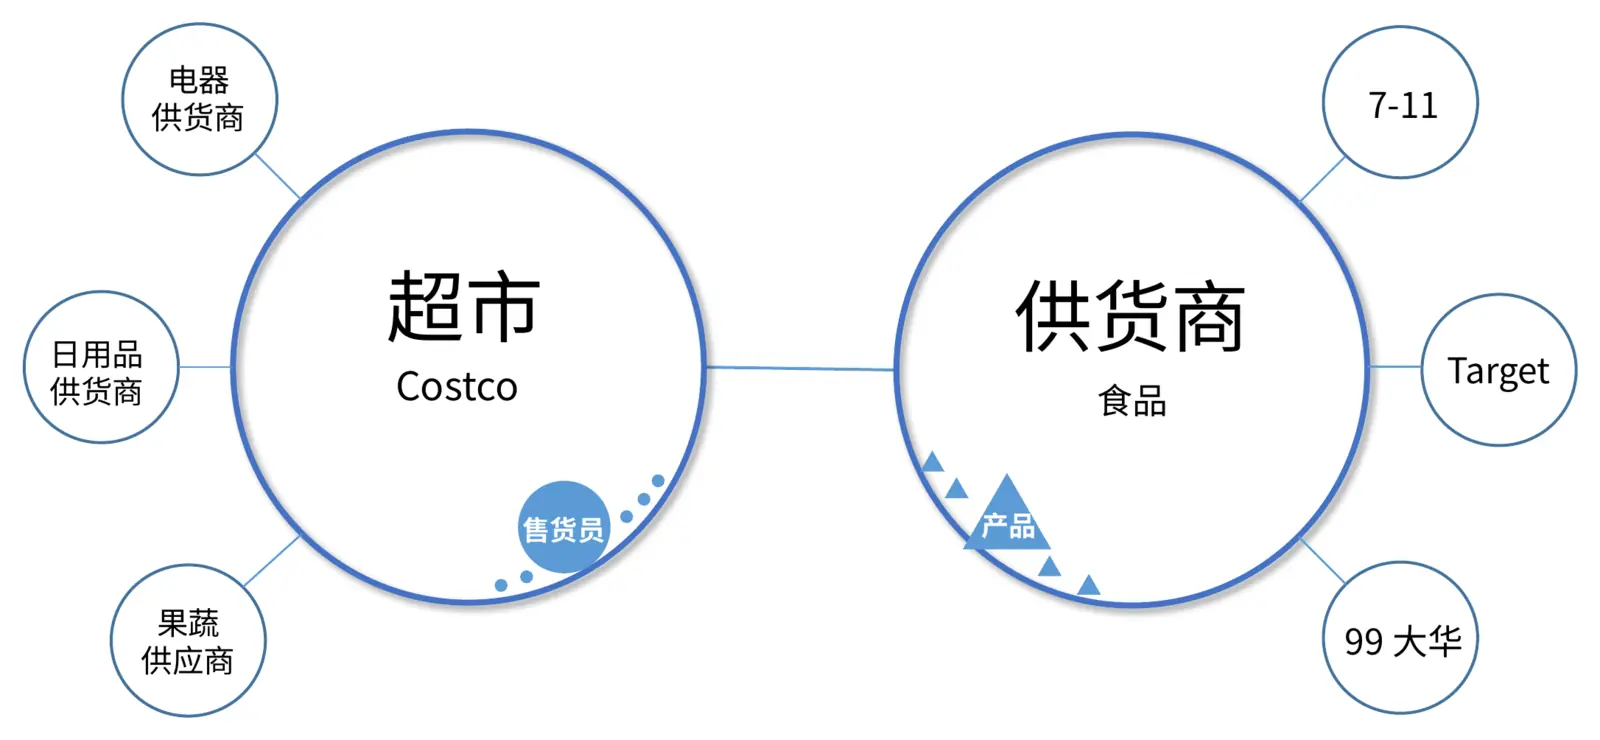
超市和供货商的比方:超市 Costco 从多家供货商进货,供货商也供货给 7-11、Target、99 大华 / Analogy: a store like Costco buys from many suppliers, and a supplier also sells to 7-Eleven, Target and 99 Ranch

上一页如果还有人觉得抽象,这一页换一个大家天天见的比方:超市和供货商。

If the last slide still felt abstract, here's an analogy everyone sees every day: stores and suppliers.

左边是超市,比如 Costco。Costco 自己不生产电视、不种水果,它向很多家供货商进货:电器有电器的供货商,日用品有日用品的,果蔬有果蔬的。 它的价值在于帮你把好东西挑好、摆在一起,你进一家店就能比较。

On the left is the store, say Costco. Costco doesn't make TVs or grow fruit. It buys from many suppliers: one for electronics, one for household goods, one for produce. Its value is choosing good products and putting them side by side, so you can compare in one place.

右边是供货商,比如一家食品厂。它做出来的同一款商品,不会只放在一家店卖,7-Eleven 有、Target 有、99 大华也有。 商品的品质是供货商负责的,不是货架负责的。

On the right is the supplier, say a food maker. It doesn't sell its product through just one store: the same item is at 7-Eleven, at Target and at 99 Ranch. The supplier answers for the quality of what it makes; the shelf doesn't.

把它对应回保险,就是下面这张表:超市就是代理商,售货员就是经纪人,供货商就是保险公司,商品就是保险产品。 经纪人像一位懂行的售货员,帮客户在货架上比较;但保单的条款、保障和理赔,是"供货商"也就是保险公司负责的。

Map it back to insurance with the table below: the store is the agency, the clerk is the agent, the supplier is the insurer and the goods are the policy. An agent is like a knowledgeable clerk who helps the client compare what's on the shelf, but the policy's terms, cover and claims are the supplier's responsibility, meaning the insurer's.

这个比方还能顺便回答一个常见问题:"既然你们可以卖很多家,为什么常常推荐同一家?"道理就像超市里某个牌子卖得特别好: 售货员有得选,顾客也有得选,它还是卖得最多,通常说明东西确实好。后面讲销量排名时,我们会回到这一点。

The analogy also answers a common question: "If you can sell many companies, why do you so often recommend the same one?" It's like a brand that outsells everything else in a store. The clerk has choices and so does the shopper, and it still sells the most, which usually means it's genuinely good. We'll come back to this with the sales rankings.

互动设计Interaction

遮住下面那张表,请一位伙伴说出四组对应:超市、售货员、供货商、商品,各对应保险里的谁。

Cover the table and ask someone to give the four pairs: store, clerk, supplier and goods, and who each is in insurance.

PFA 和国家人寿的关系PFA and National Life

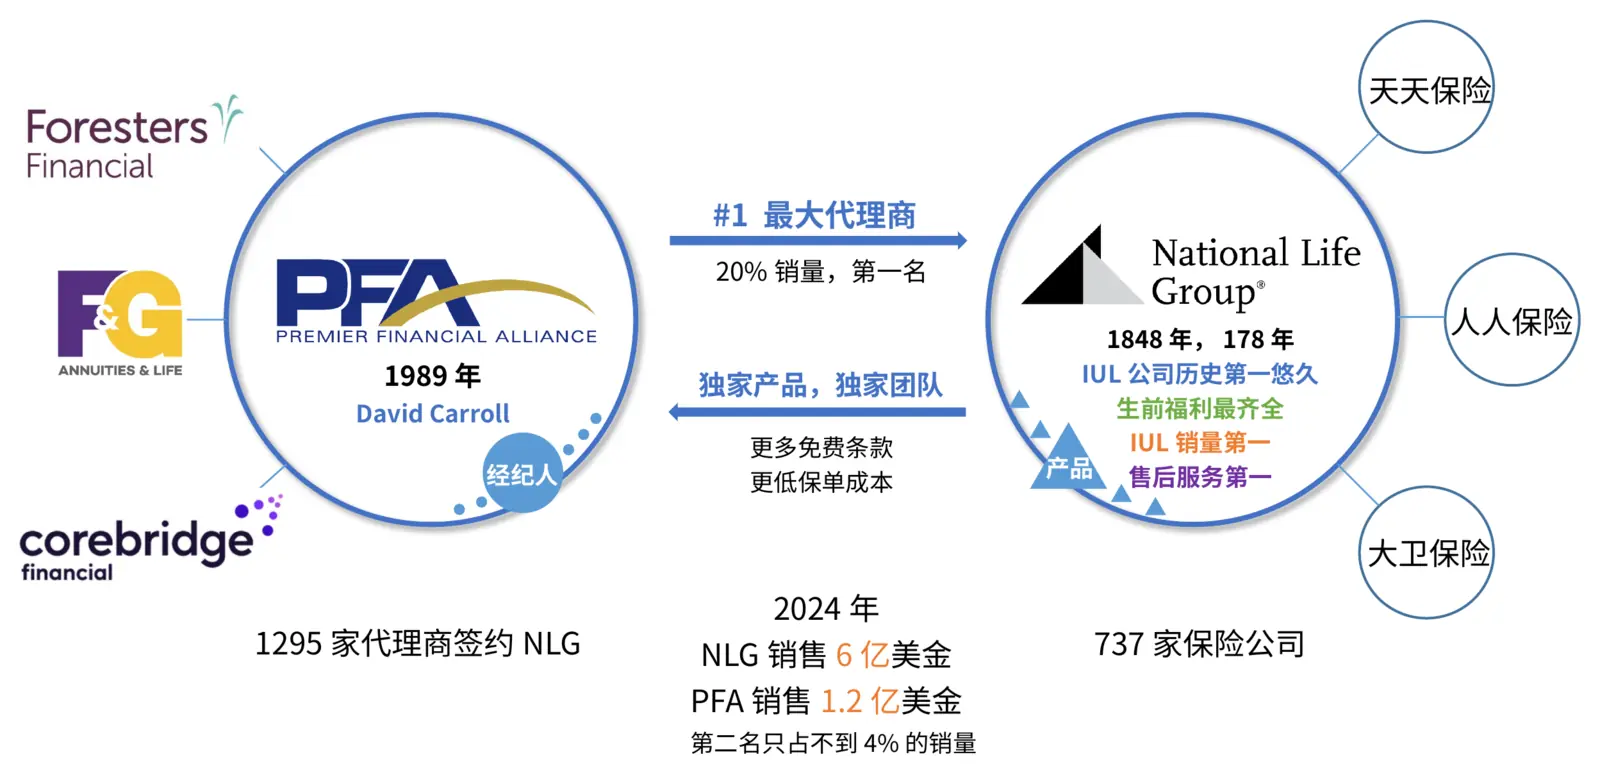
PFA 和国家人寿的关系示意图:PFA 是国家人寿最大的代理商,国家人寿给 PFA 独家产品 / Diagram: PFA is National Life's largest agency, and National Life gives PFA an exclusive product

把前两页的比方落到我们自己身上:PFA 是代理商,国家人寿是保险公司。

Now apply the analogy to ourselves: PFA is the agency; National Life is the insurer.

左边是 PFA,Premier Financial Alliance,1989 年成立。它和其他代理商一样,同时和好几家保险公司签约,所以我们手上不只有一家公司的产品。 右边是国家人寿 National Life Group,1848 年在佛蒙特州成立,到今天 178 年。全美有 1,295 家代理商和国家人寿签约,PFA 是其中之一。

On the left is PFA, Premier Financial Alliance, founded in 1989. Like any agency, it's contracted with several insurers, so we don't carry just one company's products. On the right is National Life Group, founded in Vermont in 1848, 178 years ago. Some 1,295 agencies are contracted with National Life, and PFA is one of them.

两边的关系是双向的。从 PFA 往右看:PFA 是国家人寿最大的代理商;2024 年国家人寿全年的寿险销售是 6.35 亿美金(加权新年化保费)。 图下方是 PFA 自己的数字:2024 年 PFA 的销售约 1.2 亿美金,大约占国家人寿销量的 20%,排第一;按原稿的说法,第二名占不到 4%。

The relationship runs both ways. Looking right from PFA: PFA is National Life's largest agency; National Life's 2024 life sales were $635 million (weighted new annualized premium). Below the diagram are PFA's own figures: in 2024 PFA sold about $120 million, roughly 20% of National Life's sales and the most of any agency; according to the original slide, the runner-up had under 4%.

从国家人寿往左看:因为 PFA 体量大,国家人寿给了 PFA 一款专属产品 Living Life Defender。它是 PFA 独家的指数型万能寿险,带七项独家条款。 这些条款具体是什么,在产品详解那一篇里讲。

Looking left from National Life: because PFA is so large, National Life gave PFA an exclusive product, Living Life Defender. It's an indexed universal life policy sold only through PFA, with seven exclusive riders. What those riders are is covered in the product article.

讲这一页的重点不是"我们多大",而是让客户明白:我们和国家人寿之间是长期、深度的合作,我们熟悉它的产品、核保和理赔流程, 遇到问题有渠道找到人。这对客户是实际的好处。

The point of this slide isn't "look how big we are." It's for the client to understand that the relationship with National Life is long and deep: we know its products, underwriting and claims process, and when something goes wrong we know whom to call. That is a real benefit to the client.

讲师提醒Presenter note

图是原稿截图。PFA 的销售额、20% 占比和「第二名不到 4%」来自公司内部资料,找不到公开出处,只在团队内部培训讲,不要对客户或在公开场合引用。图上「IUL 公司历史第一悠久」「售后服务第一」「更低保单成本」同样找不到出处,不要讲。PFA 的成立年份按 1989 年讲(有的资料写 2003 年,不用)。

The image is the original slide. PFA's sales, its 20% share and "runner-up under 4%" come from internal company material with no public source: use them in team training only, never with clients or in public. The claims on it about the "oldest IUL carrier," "#1 in service" and "lower policy cost" have no source we can find either, so leave them out. Give PFA's founding year as 1989 (some material says 2003; don't use it).

互惠公司 vs 股份上市公司Mutual vs. Stock Companies

互惠公司Mutual company

  • 持有人:保单持有人
  • 分红:分红型保单才有,通常不交税
  • 目标:保障保单持有人的利益
  • Owned by: policyholders
  • Dividends: participating policies only, usually untaxed
  • Aim: serve policyholders

例:National Life Group、New York Life、MassMutual、Northwestern Mutual

e.g. National Life Group, New York Life, MassMutual, Northwestern Mutual

股份上市公司Stock company

  • 持有人:股东、股票持有者
  • 分红:属于股息,要交税;保单持有人无份
  • 目标:为股东盈利
  • Owned by: shareholders
  • Dividends: taxable stock dividends; policyholders get none
  • Aim: profit for shareholders

例:Transamerica、Corebridge (AIG)、Lincoln、Brighthouse (MetLife)

e.g. Transamerica, Corebridge (AIG), Lincoln, Brighthouse (MetLife)

参考:Investopedia《Mutual vs. Stock Insurance Companies》See: Investopedia, "Mutual vs. Stock Insurance Companies"

现在进入第一个理由,也是最容易被忽略的一个:公司的所有权结构。保险公司通常是两种结构之一,互惠公司,或者股份公司。两者的根本差别只有一句话:公司在为谁赚钱。

Now the first reason, and the most overlooked: ownership. An insurer is usually one of two kinds, mutual or stock. The difference comes down to one thing: whom the company earns for.

先看第一项,公司持有人。互惠公司没有外部股东,公司归保单持有人所有。股份公司归股东所有, 股票可能在交易所上市,也可能是集团的子公司。

First: who owns it. A mutual has no outside shareholders; it belongs to its policyholders. A stock company belongs to shareholders, whether its shares trade on an exchange or it's a subsidiary of a larger group.

第二项,分红。互惠公司经营得好,可以把一部分盈余以分红的方式返还给分红型保单的持有人。在税务上,这类分红一般被看作保费返还,通常不需要交税。 股份公司的利润以股息的方式分给股东,股东要交税;保单持有人不是股东,没有份。

Second: dividends. When a mutual does well, it can return part of its surplus as dividends to holders of participating policies. For tax purposes these are generally treated as a return of premium and usually aren't taxable. A stock company pays its profit to shareholders as taxable stock dividends; policyholders aren't shareholders and get none of it.

第三项,公司目标。互惠公司的目标是保障保单持有人的利益,股份公司的目标是为股东盈利。这不是说股份公司不好,它们往往规模更大、融资能力更强。 但当公司要在"这一季度的股东回报"和"三十年后的保单持有人"之间做取舍时,两种结构的默认答案不一样。对一张要持有半个世纪的保单来说,这个默认答案很重要。

Third: the aim. A mutual exists to serve its policyholders; a stock company exists to earn for its shareholders. That doesn't make stock companies bad; they're often larger and better able to raise capital. But when a company must choose between this quarter's shareholder return and a policyholder thirty years out, the two structures have different default answers. For a policy held for half a century, that default matters.

每一栏最下面列了几家代表公司。互惠公司有国家人寿、纽约人寿、万通、西北互惠;股份公司有 Transamerica、Corebridge(原 AIG 寿险业务)、林肯、Brighthouse(从 MetLife 分拆出来)。

At the foot of each panel are some examples. Mutuals: National Life, New York Life, MassMutual and Northwestern Mutual. Stock companies: Transamerica, Corebridge (formerly AIG's life business), Lincoln and Brighthouse (spun off from MetLife).

合规提醒Compliance

分红只发给分红型保单,而且不保证。指数型万能险(IUL)一般不参与分红,它的增长来自指数记息。不要对 IUL 客户说"互惠公司会给你分红"。 讲股份公司时只讲结构,不评价具体哪家公司好不好。

Dividends go only to participating policies, and they aren't guaranteed. Indexed universal life generally doesn't participate; its growth comes from index crediting. Never tell an IUL client "the mutual will pay you dividends." When you discuss stock companies, describe the structure; don't judge any named company.

一层一层筛下来Filtering Down, Step by Step

719 家寿险公司在全美life insurers in the U.S.
532 家是股份公司are stock companies
110 家是互惠公司are mutuals
31 家互惠公司,有末期和慢性疾病生前福利mutuals offer terminal and chronic illness benefits
9 家,再加上重大疾病生前福利also offer critical illness
1 家,同时有末期、慢性、重大疾病生前福利,加永续收入、阿兹海默、不孕不育条款has terminal, chronic and critical illness benefits plus perpetual income, Alzheimer's and fertility riders

公司总数与类型:ACLI《2025 Life Insurers Fact Book》· 条款筛选来自承保公司资料,同业条款每年在变Counts and types: ACLI 2025 Life Insurers Fact Book · rider screen from carrier material; competitors' riders change every year

上一页讲了互惠和股份的区别,这一页把全美的寿险公司一层一层筛下来,看看国家人寿站在哪个位置。

Having covered mutual versus stock, this slide filters every U.S. life insurer down, layer by layer, to show where National Life stands.

第一层,全美一共 719 家寿险公司。第二层,其中 532 家是股份公司。第三层,互惠公司只有 110 家,剩下的是其他组织形式。 这三个数字来自美国人寿保险协会 ACLI 的《2025 Life Insurers Fact Book》。可以看到,互惠结构并不罕见,但绝对是少数。

Layer one: 719 life insurers in all. Layer two: 532 of them are stock companies. Layer three: only 110 are mutuals; the rest are fraternal societies and other forms. Those three numbers are from the ACLI's 2025 Life Insurers Fact Book. The mutual form isn't rare, but it's clearly a minority.

再往下看生前福利。110 家互惠公司里,同时有末期疾病和慢性疾病生前福利的是 31 家;再加上重大疾病的,剩 9 家。

Now living benefits. Of the 110 mutuals, 31 offer both terminal and chronic illness benefits; add critical illness and 9 remain.

最后一层是 1。这个"1"的定义,要一字一句讲准:同时具备末期疾病、慢性疾病、重大疾病三类生前福利, 再加上永续收入条款、阿兹海默条款和不孕不育条款的互惠公司,按这组条件筛,只有一家,就是国家人寿。

The last layer is 1. State its definition exactly: a mutual that offers terminal, chronic and critical illness living benefits together with a perpetual income rider, an Alzheimer's rider and a fertility rider. Screened on that combination, there is one company, and it's National Life.

这个"1"说的是一组条款的组合,不是说国家人寿是"全美最好的公司",也不是说别家没有生前福利。很多公司都有末期、慢性甚至重疾条款,只是组合不同。 条款每年都在变,引用这张图时要说清楚年份和筛选条件。

That "1" is about a combination of riders. It doesn't mean National Life is "the best company in America," and it doesn't mean others lack living benefits. Plenty of carriers offer terminal, chronic or even critical illness riders; the combinations differ. Riders change every year, so when you use this slide, state the year and the screening conditions.

合规提醒Compliance

这张筛选图的原稿标着 For Agent Use Only,只能在团队内部培训用,不能给客户看、不能截图转发。 对客户只讲我们自己的条款怎么写,不说"别家只有……我们才有……":贬低同业在加州属于明文禁止的行为,条款一变这句话也就不成立了。

The original of this funnel is marked For Agent Use Only. It's for internal training only: don't show it to clients or screenshot and forward it. With clients, describe what our own policy says. Don't say "others only have X, we're the only ones with Y": disparaging competitors is expressly prohibited in California, and the claim stops being true the moment riders change.

Ward's 50:财务表现前 50 名Ward's 50: Top 50 Financial Performers

1分析近 700 家寿险与健康险公司Nearly 700 life and health insurers analyzed 2安全性与一致性测试:没通过就不是候选Safety and consistency test: fail and you're out 3业绩测试:排进前 50 才上榜Performance test: only the top 50 make the list
2026 年榜单2026 list连续第 6 年6th year running
榜单 36 年历史中In the list's 36 years入选 18 次18 times
评估期Period assessed2021–2025 五年2021–2025

讲完结构,我们看第三方怎么评价这家公司。第一个是 Ward's 50。

With structure covered, let's see how outsiders rate the company. First, Ward's 50.

Ward's 是一家专门研究保险公司财务表现的机构,每年发布一份寿险与健康险公司前 50 名的榜单。它的筛选分三步,就是图上这三行: 第一步,把近 700 家寿险和健康险公司全部拿来分析,用的是客观的财务数据,加上一些质量指标。

Ward's is a firm that studies insurers' financial performance and publishes an annual list of the top 50 life and health companies. Its screen has three steps, the three lines on the slide. Step one: analyze nearly 700 life and health insurers, using objective financial data plus some quality measures.

第二步,安全性和一致性测试。这一步看的是公司稳不稳:资本是否充足、经营是否连续几年都稳定。没通过的直接出局,不进入下一步。 第三步,业绩测试。通过安全性测试的公司再比经营表现,排进前 50 名才上榜。

Step two: the safety and consistency test, which asks whether the company is steady: adequately capitalized and stable year after year. Fail it and you're out. Step three: the performance test. Companies that passed are compared on results, and only the top 50 make the list.

国家人寿入选了 2026 年的 Ward's 50,这是它连续第 6 年上榜。这份榜单做了 36 年,国家人寿一共入选 18 次。 2026 年这次评估看的是 2021 到 2025 这五年的数据。以上来自国家人寿 2026 年 7 月 10 日的新闻稿。

National Life made the 2026 Ward's 50, its sixth straight year. In the list's 36 years, National Life has been on it 18 times. The 2026 assessment covered the five years from 2021 through 2025. All of this is from National Life's July 10, 2026 press release.

这一页为什么重要?因为它先看安全,再看业绩。一家公司卖得再多,如果安全性不过关,第二步就被刷掉了。 对我们的客户来说,这正是他们最关心的顺序:先确认公司稳,再谈产品好不好。

Why does this matter? Because safety comes first and performance second. However much a company sells, if it fails on safety it's gone at step two. That's exactly the order our clients care about: first make sure the company is sound, then talk about the product.

讲师提醒Presenter note

原稿写"超过 700 家",2026 年新闻稿的说法是"近 700 家"(nearly 700),按新闻稿讲。说 Ward's 50 时带上年份。

The original said "more than 700"; the 2026 release says "nearly 700," so use that. Always give the year when you cite Ward's 50.

三家评级机构:A+ · A+ · A1Three Rating Agencies: A+ · A+ · A1

评级机构Agency评级Rating在该机构量表中的位置Position on its scale
A.M. BestA+ (Superior)16 级中第 2 级2nd of 16
S&PA+ (Strong)21 级中第 5 级5th of 21
Moody'sA1 (Good)21 级中第 5 级5th of 21

代表公司经济实力强,前景稳固Strong finances and a stable outlook

评级日期 2025 年 10 月 11 日 · 评级会变,引用前到公司官网核对Ratings as of October 11, 2025 · they change, so check the company site before quoting

保险公司的承诺,是一张几十年后才兑现的支票。所以除了公司自己怎么说,我们更要看专业评级机构怎么说。这一页是三家主要评级机构给国家人寿的财务实力评级。

An insurer's promise is a check that clears decades from now. So beyond what the company says about itself, we look at what the professional rating agencies say. This slide shows the financial-strength ratings from the three main agencies.

第一家,A.M. Best,专门评保险公司的老牌机构,给的是 A+,叫 Superior,在它 16 个等级里排第 2 级。 第二家,标普 S&P,给的是 A+,叫 Strong,在 21 个等级里排第 5 级。 第三家,穆迪 Moody's,给的是 A1,叫 Good,在 21 个等级里也是第 5 级。

First, A.M. Best, the long-established agency that rates insurers specifically: A+, "Superior," the 2nd of its 16 grades. Second, S&P: A+, "Strong," 5th of 21. Third, Moody's: A1, "Good," also 5th of 21.

请注意,穆迪的写法和另外两家不一样,它用的是 A1,不是 A+。A1 在穆迪的量表里,和标普的 A+ 是同一档。 所以准确的说法是"A.M. Best 和标普 A+,穆迪 A1",不要说成"三家全部 A+"。

Note that Moody's uses a different notation: A1, not A+. On Moody's scale, A1 sits at the same tier as S&P's A+. So the accurate statement is "A+ from A.M. Best and S&P, A1 from Moody's." Don't say "A+ from all three."

这三个评级说明什么?说明在专业机构眼里,国家人寿的资本充足、偿付能力强、前景稳定。 评级不是一成不变的,每年都会复评。这里的日期是 2025 年 10 月 11 日,给客户引用之前,请先到公司官网核对最新评级,并把日期一起说出来。

What do these ratings say? That in the agencies' view National Life is well capitalized, able to pay, and stable. Ratings aren't fixed; they're reviewed every year. These are as of October 11, 2025. Before quoting them to a client, check the latest on the company site and state the date.

互动设计Interaction

请一位伙伴用一句话把三家评级准确说出来,包括穆迪那一项。

Ask one person to state all three ratings accurately in one sentence, Moody's included.

Forbes 2024 与行业排名Forbes 2024 and Industry Rankings

Forbes 2024 America's Best Insurance Companies 徽章,Powered by Statista / Forbes 2024 America's Best Insurance Companies badge, powered by Statista
Forbes 与 Statista 消费者调查评选Forbes and Statista consumer survey
#1IUL 销量(Wink,2024 Q4)IUL sales (Wink, Q4 2024)
#1IUL 市场份额(Wink,2024 Q4)IUL market share (Wink, Q4 2024)
#8全美个人寿险销量(LIMRA)U.S. individual life sales (LIMRA)

这一页有两类信息,性质不一样,请分开讲。

This slide holds two kinds of information, and they're different in nature. Take them separately.

左边是一个奖项:国家人寿入选了福布斯 Forbes 的 "America's Best Insurance Companies 2024",也就是"美国最佳保险公司"榜单。 这份榜单是 Forbes 和数据公司 Statista 合作做的,方法是消费者调查:问了一万五千多位消费者,请他们评价过去三年用过的保险公司,看推荐意愿、满意度和忠诚度。 2024 年一共有 155 家公司在五类保险里获奖。

On the left is an award: National Life was named to Forbes' "America's Best Insurance Companies 2024." Forbes compiles the list with the data firm Statista, using a consumer survey: more than 15,000 people rated insurers they'd used in the past three years on willingness to recommend, satisfaction and loyalty. In 2024, 155 companies were recognized across five lines of insurance.

所以这个奖说明的是客户体验,不是财务实力。讲的时候要讲准:"这是消费者评出来的口碑榜",不要把它说成财务排名。

So this award speaks to customer experience, not financial strength. Say it precisely: "this is a reputation list voted by consumers." Don't present it as a financial ranking.

右边是行业排名,出处是行业数据机构。按 Wink 2024 年第四季度的报告,国家人寿的指数型万能险 IUL 销量第一、市场份额也是第一。 按 LIMRA 的统计,它在全美个人寿险销量里排第八。注意这个第八是所有寿险产品加在一起排的,第一名是只算 IUL 这一类。

On the right are industry rankings from industry data firms. Per Wink's Q4 2024 report, National Life was #1 in IUL sales and #1 in IUL market share. Per LIMRA, it ranked #8 in U.S. individual life sales. Note that the #8 counts all life products together, while the #1s count IUL alone.

这三个排名,和左边的福布斯奖项是两件独立的事,不是福布斯评出来的。把出处分清楚,客户一查就对得上。

These three rankings are separate from the Forbes award; Forbes didn't produce them. Keep the sources straight, and a client who checks will find they match.

讲师提醒Presenter note

原稿把右边四个排名都放在"福布斯评估"下面,出处不对;其中一条英文原文是"雇主计划里的固定指数年金第一", 被翻成了"指数型年金销量第一",范围被放大了,而且找不到出处,这里删掉。

The original put all four rankings under "Forbes," which is the wrong source. One of them read "#1 for fixed indexed annuities in employer-sponsored plans" and was translated as "#1 in indexed annuity sales," which widens the claim; we can't find its source either, so it's dropped.

Wink:指数型寿险销量第一Wink: #1 in Indexed Life Sales

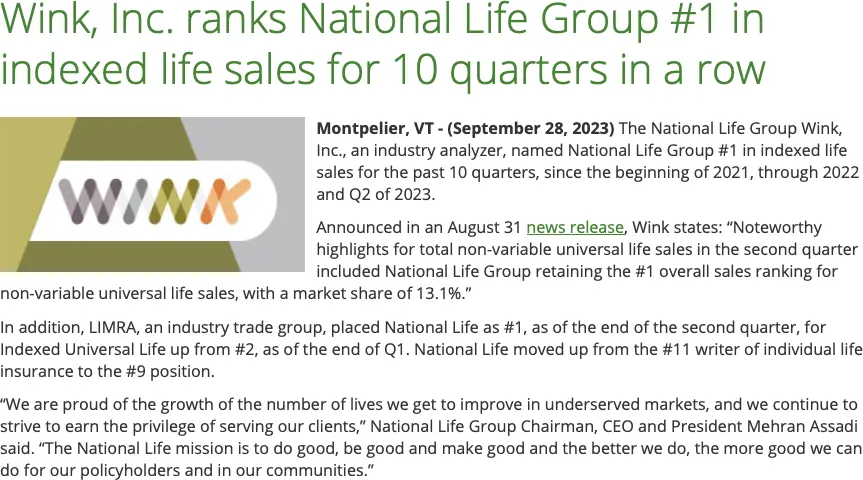
国家人寿 2023 年 9 月 28 日新闻稿:Wink 把国家人寿评为连续 10 个季度指数型寿险销量第一 / National Life news release, September 28, 2023: Wink ranks National Life Group #1 in indexed life sales for 10 quarters in a row
公司新闻稿 · 2023 年 9 月 28 日Company release · September 28, 2023
10 个季度:2021 Q1–2023 Q2 连续第一10 quarters: #1 from Q1 2021 to Q2 2023
15.3%:2025 Q4 份额,排名第一15.3%: Q4 2025 share, ranked #1
15.7%:2026 Q2 份额,排名第一15.7%: Q2 2026 share, ranked #1

上一页提到 Wink,这一页专门讲它。Wink 是一家行业数据公司,每个季度统计各家保险公司指数型产品的销量,并公布排名。

The last slide mentioned Wink; this one is about it. Wink is an industry data firm that tallies each insurer's sales of indexed products every quarter and publishes the rankings.

左边是国家人寿 2023 年 9 月 28 日的新闻稿:Wink 把国家人寿评为指数型寿险销量第一,从 2021 年第一季度到 2023 年第二季度,连续 10 个季度。 新闻稿里还提到,那一季度它在非变额万能险整体销量里也排第一,份额 13.1%;LIMRA 那时也把它的 IUL 排在第一。

On the left is National Life's September 28, 2023 release: Wink ranked National Life #1 in indexed life sales for 10 straight quarters, from Q1 2021 through Q2 2023. The release adds that in that quarter it was also #1 in total non-variable universal life sales, with a 13.1% share, and that LIMRA ranked it #1 in IUL at the time.

右边是之后的情况:我们查到的每一份季度报告里,它仍然排第一。2025 年第四季度,它在指数型寿险的市场份额是 15.3%; 最新的 2026 年第二季度是 15.7%。七百多家寿险公司里,一家公司拿到大约七分之一的份额,并且多年保持第一。

On the right is what came after: in every quarterly report we've checked, it's still #1. In Q4 2025 its share of indexed life sales was 15.3%; in the latest, Q2 2026, it was 15.7%. Among more than seven hundred life insurers, one company holding about a seventh of the market and staying first for years.

回到超市的比方:大多数代理商同时代理好几家公司的产品,经纪人有选择,客户也有选择。在这样完全竞争的货架上,一款产品能多年卖得最多, 说明在核保、理赔、产品设计和售后这些方面,它确实有可取之处。销量本身不等于产品好,但它说明很多专业的人在有选择的情况下,反复选了它。

Back to the store analogy: most agencies carry several companies' products, so agents have choices and so do clients. On a fully competitive shelf like that, a product that sells the most year after year is doing something right in underwriting, claims, design and service. Sales alone don't prove a product is good, but they show that many professionals, with options, keep choosing it.

合规提醒Compliance

只说"Wink 排名第一",并带上季度和份额。比 10 个季度更长的连续季度数找不到公开出处,不要引用。 13.1% 是 2023 年第二季度非变额万能险整体的份额,不是 IUL 份额,不要混用。

Say "#1 per Wink" with the quarter and the share. Longer streaks than 10 quarters have no public source; don't quote them. The 13.1% is Q2 2023's share of all non-variable universal life, not of IUL alone; don't mix them up.

America's Magnificent Eight(2018)America's Magnificent Eight (2018)

国家人寿网站横幅:National Life is one of the Magnificent Eight,America's Magnificent Eight Exceptional Businesses 标志 / National Life website banner: National Life is one of the Magnificent Eight, with the America's Magnificent Eight Exceptional Businesses logo
CEO Forum 评选 · 2018 年Named by The CEO Forum · 2018

评选方对"卓越企业"的定义:

How the selectors define an exceptional business:

融合真实文化、开创性的客户体验、
持久的财务实力,
以及超越商业的目标。

"An integration of authentic culture, groundbreaking customer experience, enduring financial strength, and purpose that transcends business."

这一页讲一个和财务数字不一样的角度:企业文化和使命。

This slide takes a different angle from the financial figures: culture and purpose.

2018 年,CEO Forum 把国家人寿评为 "America's Magnificent Eight",也就是"全美八家杰出企业"之一。CEO Forum 是一家专门报道企业 CEO 的媒体机构, 当时它考察了大约七百五十位 CEO 和他们的公司,最后选出八家;入选公司的 CEO 们在 Forbes.com 的专栏里分享了经营心得,国家人寿的 CEO 就是其中之一。

In 2018, The CEO Forum named National Life one of "America's Magnificent Eight" exceptional companies. The CEO Forum is a media group that covers chief executives; it considered about 750 CEOs and their companies and chose eight. The selected CEOs then shared their thinking in a column on Forbes.com, and National Life's CEO was among them.

右边是评选方对"卓越企业"的定义,一共四件事:真实的文化、开创性的客户体验、持久的财务实力、超越商业的目标。 我们把"持久的财务实力"标了出来,因为它和前面讲的评级、Ward's 50 是同一个意思。

On the right is the selectors' definition of an exceptional business, four things: authentic culture, groundbreaking customer experience, enduring financial strength and purpose beyond business. We've highlighted "enduring financial strength" because it echoes the ratings and Ward's 50 we just covered.

为什么这一点对客户有意义?因为一家公司愿意把使命放在前面,它在理赔时的态度通常也不一样。国家人寿的使命说法是"do good, be good, make good", 翻成大白话就是:做好事、做好人、说到做到。

Why does that matter to a client? A company that puts its mission first usually behaves differently when a claim comes in. National Life's stated mission is "do good, be good and make good": do good work, be a good company, and keep your word.

讲师提醒Presenter note

原稿写"被福布斯 CEO 论坛评为"。准确的说法是:2018 年由 CEO Forum 评选,相关专栏刊登在 Forbes.com。不要说成"福布斯评的"。

The original said "named by the Forbes CEO Forum." Accurately: The CEO Forum chose the companies in 2018, and the related column ran on Forbes.com. Don't say "Forbes named it."

国家人寿生前福利 30 年Thirty Years of Living Benefits

1991首推末期疾病条款,预期寿命 12 个月First terminal illness rider, 12-month life expectancy 1997首推慢性疾病条款(与末期组合),末期放宽到 24 个月Chronic illness added (combined with terminal); terminal extended to 24 months 2000末期更新到今天的版本;首个独立慢性条款,等待期 5 年Terminal updated to today's version; first standalone chronic rider, 5-year wait 2003首推重大疾病条款First critical illness rider 2007慢性等待期缩短到 2 年Chronic wait cut to 2 years
2008纽约州最早提供慢性疾病条款的公司之一Among the first to offer a chronic rider in New York 2013末期与慢性理赔上限从 $100 万提高到 $150 万Terminal and chronic cap raised from $1M to $1.5M 2015重大疾病扩项,首推重大伤害Critical illness expanded; critical injury added 2017慢性等待期缩短到 30 天Chronic wait cut to 30 days 2023首推阿兹海默条款First Alzheimer's rider

前面讲的是公司稳不稳、卖得好不好,这一页讲条款深度:国家人寿在生前福利上,一步一步做了三十多年。

So far we've covered whether the company is sound and whether it sells. This slide is about depth: National Life has built its living benefits step by step for more than thirty years.

1991 年,第一次推出末期疾病条款,条件是预期寿命 12 个月。1997 年,第一次推出慢性疾病条款,和末期条款组合在一起,同时把末期的门槛放宽到 24 个月预期寿命。 2000 年,末期条款更新到我们今天用的版本,第一个独立的慢性疾病条款出现,当时等待期是 5 年。2003 年,第一次推出重大疾病条款。 2007 年,慢性条款的等待期从 5 年缩短到 2 年。

In 1991 came the first terminal illness rider, with a 12-month life expectancy threshold. In 1997 the first chronic illness rider, combined with the terminal rider, and the terminal threshold was extended to 24 months. In 2000 the terminal rider was updated to the version we use today, and the first standalone chronic rider appeared, with a five-year waiting period. In 2003, the first critical illness rider. In 2007 the chronic waiting period dropped from five years to two.

2008 年,国家人寿成为纽约州最早提供慢性疾病条款的公司之一。2013 年,末期和慢性条款的理赔上限从 100 万提高到 150 万美金。 2015 年,重大疾病增加了病种,并第一次推出重大伤害。2017 年,慢性条款的等待期从 2 年缩短到 30 天,这是幅度最大的一次。2023 年,第一次推出阿兹海默条款。

In 2008 National Life became one of the first carriers to offer a chronic rider in New York. In 2013 the terminal and chronic caps rose from $1 million to $1.5 million. In 2015 critical illness gained conditions and critical injury was added. In 2017 the chronic waiting period fell from two years to 30 days, the largest single step. In 2023, the first Alzheimer's rider.

这条时间线说明的是"持续投入":三十年里不断加项目、放宽条件、缩短等待。生前福利不是哪一年突然加上去的卖点,而是公司长期在做的事。 每一项的触发条件、额度上限和实际能拿到多少,在《生前福利》那一篇里讲。

The timeline shows sustained investment: thirty years of adding benefits, easing conditions and shortening waits. Living benefits aren't a selling point bolted on one year; they're something the company has worked on for decades. Each trigger, its cap and what a claim actually pays are covered in the Living Benefits article.

合规提醒Compliance

原稿写 2017 年"等待期缩短为 90 天",不对:等待期是 30 天;90 天是慢性条款里"无法完成 2 项日常生活行为"要持续的时长,两个时间不要混在一起。 这里讲的是现行版本,老保单的条款和理赔规则可能不同。具体金额签单时给不出:以 $100 万保额为例,条款有上限,实际金额由公司按病情、年龄、剩余寿命计算。

The original said the 2017 change cut the wait "to 90 days." That's wrong: the waiting period is 30 days; the 90 days is how long the inability to perform two activities of daily living must last under the chronic rider. Keep the two apart. This describes the current versions; older policies may have different riders and claim rules. No amount can be quoted at sale: on a $1 million policy, for example, the rider has a cap, and the actual amount is computed by the carrier from the condition, age and remaining life expectancy.

钱放在哪里:资产配置Where the Money Sits

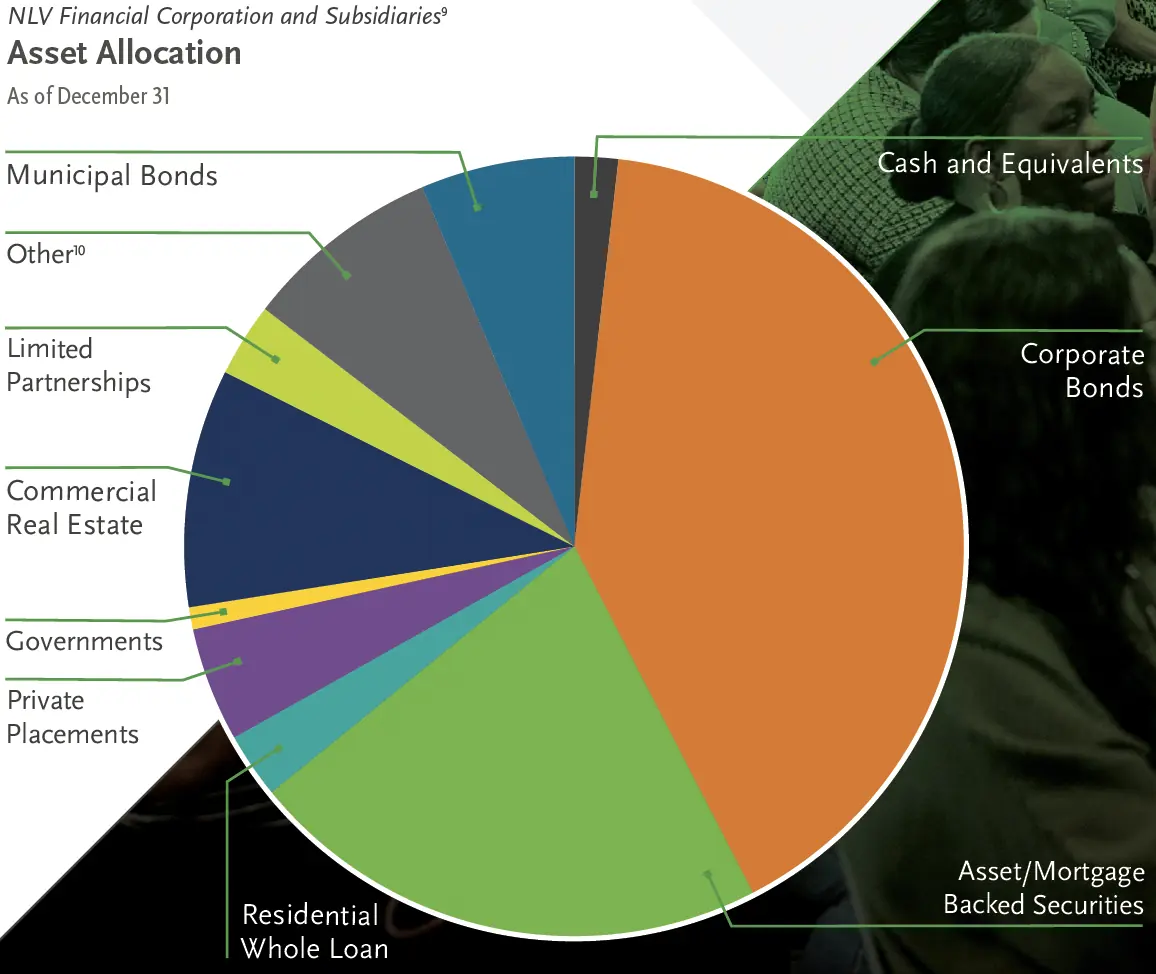
NLV Financial 及子公司资产配置饼图(截至 12 月 31 日):公司债券占比最大,其次是资产与房贷抵押证券,另有住宅整笔贷款、私募证券、政府债券、商业地产、有限合伙、其他、地方政府债券、现金 / NLV Financial asset allocation pie (as of December 31): corporate bonds largest, then asset- and mortgage-backed securities, with residential whole loans, private placements, governments, commercial real estate, limited partnerships, other, municipal bonds and cash
NLV Financial 年报 · 截至 12 月 31 日NLV Financial annual report · as of December 31
  • 公司债券(最大一类)Corporate bonds (largest)
  • 资产与房贷抵押证券Asset- and mortgage-backed securities
  • 住宅整笔贷款、商业地产Residential whole loans, commercial real estate
  • 私募证券、有限合伙Private placements, limited partnerships
  • 政府债券、地方政府债券Government and municipal bonds
  • 现金及等价物、其他Cash and equivalents, other
  • 集团投资资产 $424 亿,超过 96% 为投资级(2024 年底)$42.4B invested assets, over 96% investment grade (end of 2024)

最后一个理由:钱放在哪里。客户交给保险公司的保费,公司拿去投资什么,决定了市场动荡的时候它扛不扛得住。

The last reason: where the money sits. What an insurer does with the premium it collects decides whether it holds up when markets are rough.

左边这张饼图是国家人寿母公司 NLV Financial 及子公司的资产配置。最大的一块是公司债券,第二大的是资产和房贷抵押证券, 剩下的分散在住宅整笔贷款、商业地产、私募证券、有限合伙、政府债券、地方政府债券和现金上。"其他"这一项,按年报的脚注,包括保单贷款、衍生品、非关联普通股、房地产和住房税收抵免。

The pie on the left is the asset allocation of NLV Financial, National Life's parent, and its subsidiaries. The largest slice is corporate bonds; the second is asset- and mortgage-backed securities. The rest is spread across residential whole loans, commercial real estate, private placements, limited partnerships, government and municipal bonds, and cash. Per the report's footnote, "other" includes policy loans, derivatives, unaffiliated common stock, real estate and housing tax credits.

一句话概括:以固定收益为主。到 2024 年底,集团投资资产 424 亿美金,其中超过 96% 是投资级。

In a sentence: mostly fixed income. At the end of 2024, group invested assets were $42.4 billion, over 96% of it investment grade.

这也解释了 IUL 的"0% 下限"从哪里来:公司用债券组合稳定的收益去买指数期权。指数涨了,期权赚钱,按规则给保单记息;指数跌了,期权作废,那一年记 0%,不记负数。 但要讲清楚:0% 指的是指数记息那一部分,保单成本每个月照扣,所以记 0 的年份,现金值还是会往下走一点。

It also explains where the IUL's 0% floor comes from: the carrier uses the steady yield of its bond portfolio to buy index options. When the index rises, the options pay and the policy is credited by formula; when it falls, the options expire and that year is credited 0%, never a negative. But be clear: the 0% applies to index crediting. Policy charges still come out every month, so in a zero year the cash value still drifts down a little.

合规提醒Compliance

不要说"保本""零就是英雄,绝对不会亏"。准确的说法是:"指数那部分不记负数,但保单成本照扣,所以 0 的年份现金值还是会往下走一点。"

Don't say "principal protected" or "zero is your hero, you can never lose." Say: "The index portion never credits a negative, but charges still come out, so in a zero year the cash value still dips a little."

写过国家人寿和 PFA 的作者The Authors Who Wrote About Us

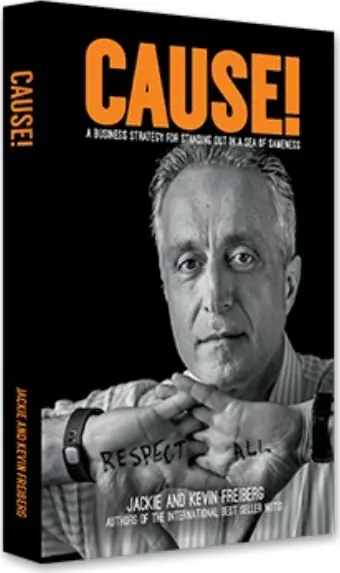
《CAUSE!》书封,作者 Jackie and Kevin Freiberg / Cover of CAUSE! by Jackie and Kevin Freiberg
《CAUSE!》以国家人寿为案例CAUSE! features National Life
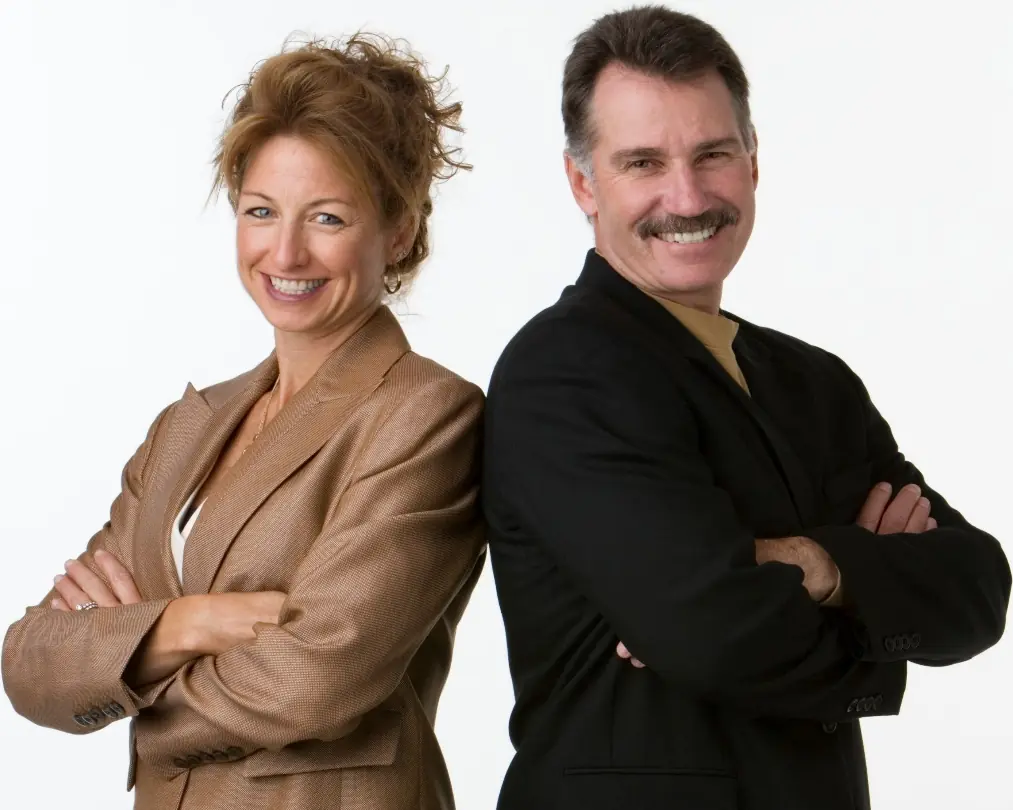
作者 Kevin 和 Jackie Freiberg 合影 / Authors Kevin and Jackie Freiberg
Kevin & Jackie Freiberg
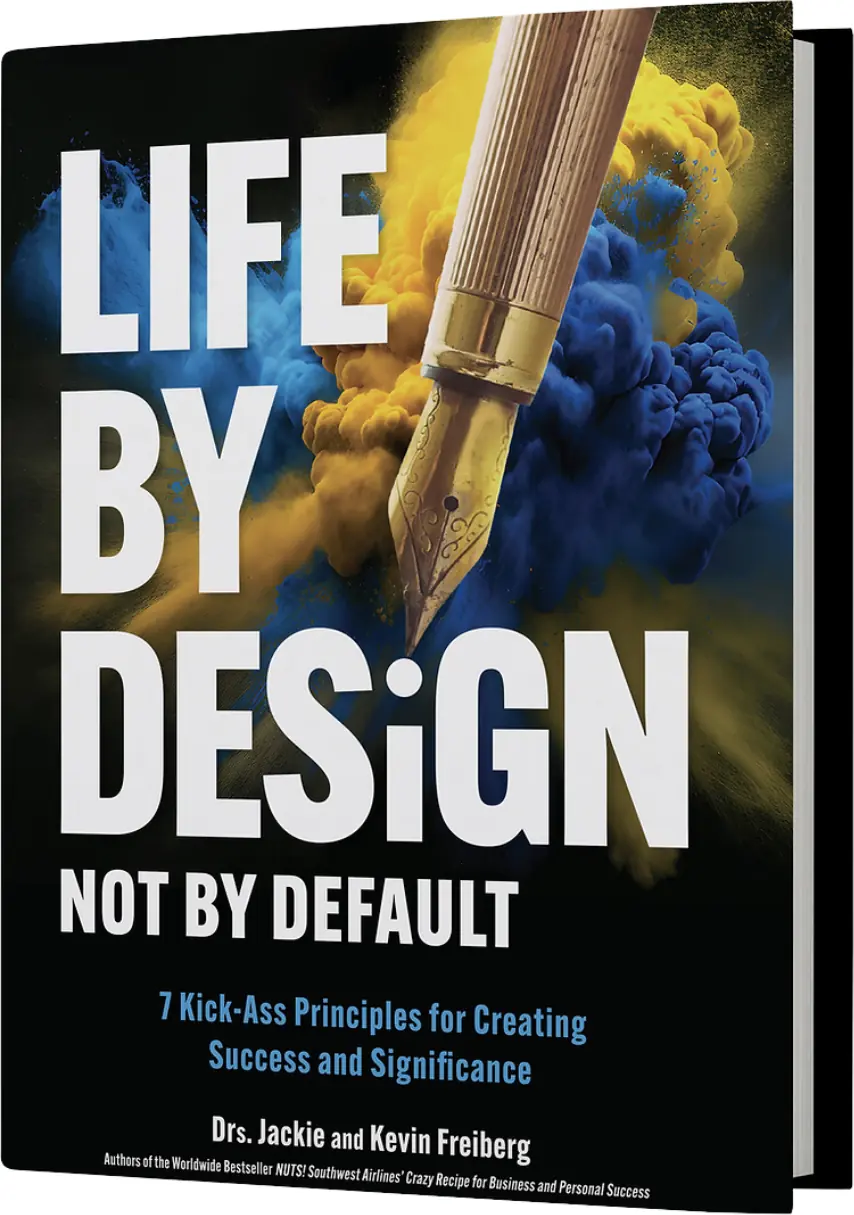
《Life by Design, Not by Default》书封,作者 Drs. Jackie and Kevin Freiberg / Cover of Life by Design, Not by Default by Drs. Jackie and Kevin Freiberg
《Life by Design, Not by Default》讲 PFALife by Design, Not by Default on PFA

最后一页,介绍两本书和它们的作者。

The last slide introduces two books and their authors.

中间这两位是 Kevin Freiberg 和 Jackie Freiberg 夫妇,美国的商业作家和演讲者,写了很多本讲企业文化、领导力的书。 他们写过的书里,包括讲美国西南航空的《NUTS!》。

In the middle are Kevin and Jackie Freiberg, a husband-and-wife team of American business writers and speakers who have written many books on company culture and leadership. Their books include NUTS!, about Southwest Airlines.

左边这本是《CAUSE!》,副标题是"在千篇一律中脱颖而出的商业策略"。书里讲的是使命驱动型的公司,国家人寿是书中的主要案例, 封面人物就是国家人寿的董事长兼 CEO。这本书写的,正是前面 Magnificent Eight 那一页讲的那种公司:把使命放在前面,同时保持持久的财务实力。

On the left is CAUSE!, subtitled "A Business Strategy for Standing Out in a Sea of Sameness." It's about purpose-driven companies, with National Life as a central case; the man on the cover is National Life's chairman and CEO. The book describes the kind of company from the Magnificent Eight slide: mission first, with enduring financial strength.

右边这本是《Life by Design, Not by Default》,副标题是"创造成功与意义的七条原则",同样是 Freiberg 夫妇写的,讲的是 PFA 这家公司和它的文化。 团队做书籍邀约时用的就是这一本,具体做法见《招募》那一篇。

On the right is Life by Design, Not by Default, subtitled "7 Kick-Ass Principles for Creating Success and Significance," also by the Freibergs, about PFA and its culture. It's the book the team uses for book-drop invitations; the method is in the Recruiting article.

讲这一页,目的是让大家知道:保险公司和我们所在的平台,都有外部作者愿意花时间研究、写进书里。想深入了解,最好的办法就是自己把这两本书读一遍。

The aim of this slide is simply to show that both the insurer and our platform have drawn outside authors to study them and write them up. If you want to know more, the best thing is to read both books yourself.

互动设计Interaction

请每位伙伴本月读完《Life by Design, Not by Default》里任意一章,下次培训用三句话分享:讲了什么、哪句话印象最深、准备怎么用。

Ask everyone to read any one chapter of Life by Design, Not by Default this month and, at the next session, share three sentences: what it said, the line that stuck, and how they'll use it.

一张永久寿险保单的生命周期可能是 50 年、70 年。 在这么长的时间尺度上,今年的封顶比别家高多少没那么要紧, 要紧的是这家公司在你 85 岁的时候还在不在、还愿不愿意按约定理赔。 这是我们评估公司的出发点。

A permanent policy can run 50 or 70 years. Over that horizon, whether this year's cap beats a competitor's matters less than whether the company is still there, and still paying as agreed, when you're 85. That's where our evaluation starts.

按这个标准,先说一件事:1848 年 11 月 13 日,佛蒙特州议会通过特许状, 国家人寿在蒙彼利埃(Montpelier, Vermont)成立。那是绿山山谷里的一个小镇, 也是全美人口最少的州府。178 年过去,公司总部仍然在那里。 页首这张图就是那个地方。一家公司会不会一直在,没有比这更直接的答案了。

By that standard, one fact comes first. National Life was chartered by the Vermont Legislature on November 13, 1848, in Montpelier, Vermont: a small town in a Green Mountain valley, and the least populous state capital in the country. A hundred and seventy-eight years later, the company is still headquartered there. The photograph at the top of this page is that place. On the question of whether a company will still be around, there isn't a more direct answer than that.

一、互惠公司 vs 股份上市公司1. Mutual vs. stock company

这是最容易被忽略、但影响最深远的一条。保险公司通常有两种所有权结构, 两者的根本差别是:公司在为谁赚钱。

This is the most overlooked structural fact, and the one with the longest reach. Insurers generally take one of two ownership forms, and the difference comes down to whom the company earns for.

互惠公司 MutualMutual company 股份上市公司 StockStock company
公司持有人Who owns it 保单持有人Policyholders 股东 / 股票持有者Shareholders
分红Dividends 属于保费返还,通常不需要交税Treated as a return of premium; generally not taxable 属于股息,需要交税;保单持有人无权获得Taxable stock dividends; policyholders aren't entitled to them
公司目标Objective 保障保单持有人的利益Serve policyholders' interests 为股东盈利Generate profit for shareholders
代表公司Examples National Life Group、New York Life、Mass Mutual、Northwestern Mutual Transamerica、Corebridge (AIG)、Lincoln、MetLife (Brighthouse)

这不是说股份上市公司不好,它们往往规模更大、资本市场融资能力更强、 在某些产品线上更有竞争力。但当一家公司需要在"这一季度的股东回报"和 "三十年后的保单持有人利益"之间做取舍时,两种结构给出的默认答案是不一样的。 对一张要持有半个世纪的保单来说,这个默认答案很重要。

This doesn't make stock companies bad; they're often larger, better capitalized through public markets, and more competitive in certain product lines. But when a company has to choose between this quarter's shareholder return and a policyholder's interest thirty years out, the two structures have different default answers. For a policy you'll hold for half a century, that default matters.

关于分红要说准:互惠公司的分红只发给分红型保单(例如分红型终身寿险),而且不保证; 指数型万能险(IUL)一般不参与分红,它的增长来自指数记息。

Be precise about dividends: a mutual pays them only on participating policies (participating whole life, for example), and they aren't guaranteed. Indexed universal life generally doesn't participate; its growth comes from index crediting.

背景数字Context

全美 719 家寿险公司中,532 家是股份公司,互惠公司 110 家。互惠结构并不罕见,但也绝不是多数。 110 家互惠公司里,有末期和慢性病生前福利的 31 家,再加重大疾病的 9 家。 公司总数与类型来源:ACLI 2025 Life Insurers Fact Book(2025 年 11 月)。

Of 719 U.S. life insurers, 532 are stock companies and 110 are mutuals. The mutual structure isn't rare, but it's far from the majority. Of those 110 mutuals, 31 offer terminal and chronic illness living benefits, and 9 add critical illness. Company counts and types: ACLI 2025 Life Insurers Fact Book (November 2025).

二、财务实力与评级2. Financial strength and ratings

保险公司的承诺是一张 50 年后才兑现的支票,所以第三方评级机构的评估非常重要。 评级机构从安全性、一致性与偿付能力多个维度评估, 国家人寿在 A.M. Best 和标普的评级都是 A+,穆迪是 A1(与 A+ 同一档), 代表公司经济实力强、前景稳固。

An insurer's promise is a check written for fifty years from now, which is why third-party ratings matter. National Life is rated A+ by A.M. Best and S&P and A1 by Moody's (the same tier as A+), indicating strong capitalization and a stable outlook.

另一个看财务表现的榜单是 Ward's 50:每年从近 700 家寿险与健康险公司里,先做安全性与一致性测试, 通过的再比经营业绩,排进前 50 名才上榜。国家人寿入选 2026 年榜单(评估 2021–2025 五年),这是连续第 6 年; 榜单 36 年的历史里,它一共入选 18 次。

Another list built on financial results is the Ward's 50: each year nearly 700 life and health insurers are screened for safety and consistency, the survivors are compared on performance, and only the top 50 make it. National Life is on the 2026 list (covering 2021–2025), its sixth straight year, and has appeared 18 times in the list's 36 years.

来源:国家人寿新闻稿,2026 年 7 月 10 日。

Source: National Life press release, July 10, 2026.

2024 年的几个行业数字:

A few industry figures for 2024:

#1IUL 销量(Wink,2024 Q4)IUL sales (Wink, Q4 2024)
#1IUL 市场份额(Wink,2024 Q4)IUL market share (Wink, Q4 2024)
#8全美个人寿险销量(LIMRA)U.S. individual life sales (LIMRA)
$32 亿$3.2B2024 年单缴递延年金销量,历史新高single-premium deferred annuity sales in 2024, a record

国家人寿入选了 Forbes 与 Statista 合作的 "America's Best Insurance Companies 2024"。 这份榜单来自一万五千多位消费者的调查,看的是推荐意愿、满意度和忠诚度,说明的是客户口碑,不是财务评级; 上面几个销量排名出自 Wink 和 LIMRA,与这份榜单无关。

National Life was named to "America's Best Insurance Companies 2024" by Forbes and Statista. The list comes from a survey of more than 15,000 consumers on recommendation, satisfaction and loyalty: it reflects customer reputation, not financial strength. The sales rankings above come from Wink and LIMRA, not from this list.

2018 年,CEO Forum(一家报道企业 CEO 的媒体机构)把国家人寿评为 "America's Magnificent Eight"(全美八家杰出企业)之一,相关专栏刊登在 Forbes.com。 评选方对"卓越企业"的定义是:"融合真实文化、开创性的客户体验、持久的财务实力, 以及超越商业的目标。"商业作家 Kevin 和 Jackie Freiberg 在《CAUSE!》一书里, 也以国家人寿为主要案例讲使命驱动型公司。

In 2018 The CEO Forum, a media group covering chief executives, named National Life one of "America's Magnificent Eight" exceptional companies, with the related column running on Forbes.com. The selectors define an exceptional business as "an integration of authentic culture, groundbreaking customer experience, enduring financial strength, and purpose that transcends business." Business writers Kevin and Jackie Freiberg also use National Life as a central case of a purpose-driven company in their book CAUSE!

评级和兑现承诺的最新数字Latest ratings and promises-kept figures

评级机构(2025-10-11)Agency (as of 10/11/2025)评级Rating在该机构量表中的位置Position on that agency's scale
A.M. BestA+ (Superior)16 级中第 2 级2nd of 16
S&PA+ (Strong)21 级中第 5 级5th of 21
Moody'sA1 (Good)21 级中第 5 级5th of 21
140 万1.4M客户(2024)customers (2024)
$29 亿$2.9B2024 年总给付total benefits paid, 2024
$1.11 亿$111M2024 年生前福利给付living benefits paid, 2024
$1.28 亿$128M2025 年生前福利给付living benefits paid, 2025

资本实力(2024 年底):国家人寿(NLIC)法定盈余约 $33 亿、法定总调整资本约 $39 亿;集团投资资产 $424 亿,其中超过 96% 是投资级。 「总给付」按年报总裁信的说法是近 $29 亿;年报图表另列了按法定口径(含准备金变动)的 $39 亿,引用时写清楚是哪个口径。

Capital (end of 2024): National Life Insurance Company's statutory surplus was about $3.3B and total adjusted capital about $3.9B; group invested assets were $42.4B, over 96% investment grade. "Total benefits" is nearly $2.9B in the CEO letter; a chart in the same report shows $3.9B on a statutory basis including reserve changes, so say which one you're quoting.

评级会变,引用前到公司官网核对并写上日期。

Ratings change; check the company site and state the date before quoting.

三、市场地位:指数型寿险销量第一3. Market position: #1 in indexed life

行业数据公司 Wink 每季度公布销量排名。国家人寿从 2021 年第一季度到 2023 年第二季度连续 10 个季度排名第一; 之后每一份我们查到的季度报告里它仍然是第一,最新的 2026 年第二季度指数型寿险市场占比 15.7%(2025 年第四季度 15.3%)。 在 700 多家寿险公司里,单一公司拿到约七分之一的份额、多年保持第一,这不是运气。

Wink publishes sales rankings every quarter. National Life was #1 for 10 straight quarters from Q1 2021 through Q2 2023, and it has stayed #1 in every later quarterly report we checked, most recently Q2 2026, at a 15.7% share of indexed life sales (15.3% in Q4 2025). In a field of more than 700 life insurers, holding about a seventh of the market and staying first year after year isn't luck.

来源:Wink 季度寿险销售报告(2025 年第四季度、2026 年第二季度)。比这更长的连续季度数找不到公开出处,不要引用;说「Wink 排名第一」加上季度和份额即可。

Source: Wink quarterly life sales reports (Q4 2025, Q2 2026). Longer streaks have no public source, so don't quote them; say "#1 per Wink" with the quarter and share.

从纵向看,公司的销售规模也在持续增长。2024 年寿险销售(加权新年化保费)$6.35 亿,比 2023 年的 $5.3 亿增长 20%; 单缴递延年金销量 $32 亿,创历史新高;全年新保单 26.1 万张。

The trajectory backs this up. 2024 life sales (weighted new annualised premium) were $635 million, up 20% from $530 million in 2023; single-premium deferred annuity sales hit a record $3.2 billion; 261,000 new policies were written.

来源:National Life Group 2024 年报;NLV Financial 2024 年经审计财报(法定数字为未经审计的附注)。

Sources: National Life Group 2024 Annual Report; NLV Financial audited 2024 statements (statutory figures from the unaudited note).

为什么销量排名值得看Why sales rank is worth watching

销量本身不代表产品好,但它代表大量独立经纪人在有选择的情况下反复选了它。 全美有 1,295 家代理商与国家人寿签约,这些代理商大多同时代理多家公司的产品, 没有理由不把客户放到更好的方案里。当一家公司在完全竞争的分销渠道里连续多年排第一, 说明它在核保、理赔、产品设计和售后的综合体验上,确实有可取之处。

Sales volume doesn't prove a product is good, but it does show that a large number of independent brokers keep choosing it when they have options. Some 1,295 agencies are contracted with National Life, and most of them represent several carriers at once, with no reason to steer a client to a worse plan. A company that leads a fully competitive distribution channel year after year is doing something right across underwriting, claims, product design, and service.

顺带分清两个角色:代理商(Agency)和多家保险公司签约,经纪人挂在代理商名下,帮客户比较、选产品; 保险公司设计产品、核保、理赔,保单合同和保费都在保险公司。我们所在的 PFA 是代理商,国家人寿是保险公司。 PFA 是国家人寿最大的代理商;国家人寿也给了 PFA 一款专属产品 Living Life Defender。

It helps to separate two roles. An agency is contracted with many insurers; agents work under it and help clients compare and choose. The insurer designs the product, underwrites and pays claims; the contract and the premium sit with the insurer. PFA, where we work, is an agency; National Life is the insurer. PFA is National Life's largest agency, and National Life in turn gives PFA an exclusive product, Living Life Defender.

四、条款深度:30 年的投入4. Rider depth: thirty years of work

国家人寿在生前福利上的投入始于 1991 年,是行业里最早、也是推进最持续的公司之一。 按 ACLI 的统计口径筛选,全美只有 1 家互惠保险公司同时具备 末期疾病、慢性疾病、重大疾病的生前福利,加上永续收入条款、老年痴呆条款和不孕不育条款。

National Life's living-benefit work began in 1991, making it one of the earliest and most persistent carriers in this area. Filtered by ACLI's data, exactly one mutual insurer in the U.S. offers terminal, chronic, and critical illness living benefits together with a perpetual income rider, an Alzheimer's rider, and a fertility rider.

条款的数量也值得说一句:生前福利这一块合计 19 项触发条件:重大疾病 13 项、重大伤害 4 项、 以及阿兹海默条款涵盖的阿兹海默症与路易体痴呆 2 项, 末期疾病与慢性疾病另计。

The count is worth stating too: the living-benefit set carries 19 triggers: 13 critical illnesses, 4 critical injuries, and the 2 conditions under the Alzheimer's rider (Alzheimer's disease and Lewy body dementia), with terminal and chronic illness on top of that.

完整的条款演进时间线、每一项的触发条件与额度上限,以及理赔实际能拿到多少,见 生前福利。 当前主力产品 Living Life Defender 2.0 的七项独家条款,见 产品详解。

The full rider timeline, each trigger and its cap, and what a claim actually pays are in Living Benefits. The seven exclusive riders on the current flagship, Living Life Defender 2.0, are covered in the product article.

五、钱放在哪里:资产配置5. Where the money sits

保险公司收到保费之后,这笔钱会去哪里?这决定了它在市场动荡时的抗压能力。 国家人寿的投资组合以固定收益类资产为主,主要配置包括:

Where does premium go once the carrier receives it? That determines how well it holds up under market stress. National Life's portfolio is weighted toward fixed income, with the main allocations being:

这个结构解释了 IUL 的"保底"从哪儿来: 公司用固定收益组合的稳定回报去购买指数期权, 期权不赚钱的年份你拿 0%,但本金由债券组合托底。

This structure explains where the IUL floor comes from: the carrier uses the steady yield of a fixed-income portfolio to buy index options. In years the options expire worthless you're credited 0%, but your principal sits behind the bond portfolio.

上一篇Previous 生前福利Living Benefits 下一篇Next Living Life DefenderLiving Life Defender

本文仅供一般性财务教育使用,不构成保险、税务或投资建议;文中数字为说明性举例,具体保障与条款以保单为准。

General financial education only, not insurance, tax, or investment advice. Figures are illustrative; the policy governs.