视频讲解:Raymond。
Video walkthrough by Raymond.
- 左边:现金账户Left side: the cash value account
- 右边:保险账户Right side: the insurance account
- 大盘只是一把尺子The index is only a ruler
- 跌了要爬多久How long it takes to climb back
- 年度重置The annual reset
- 代价:封顶与保单成本The price: caps and policy costs
- 7702 与保单贷款Section 7702 and policy loans
- 两类贷款Two kinds of loans
- 两个前提Two conditions
- 回头看一遍Looking back
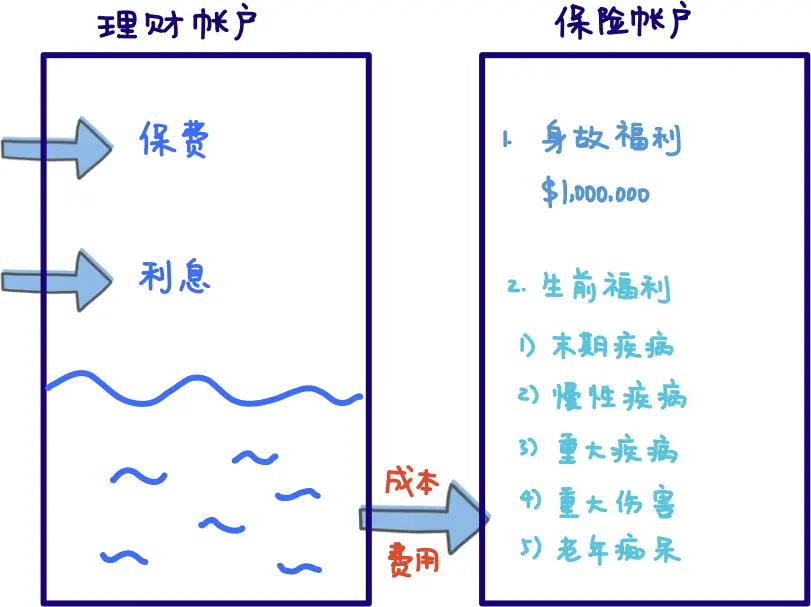
先说结论:IUL 是一张永久型人寿保险保单。你放进去的钱, 会分成两边工作:左边是现金账户,负责攒钱;右边是保险账户,负责保命。 下面把这张保单拆成两个账户,一个一个讲。
The short version: IUL is a permanent life insurance policy. The money you put in works on two sides: on the left, a cash value account that accumulates; on the right, an insurance account that protects. Below we take the policy apart into those two accounts, one at a time.
一、左边:现金账户1. Left side: the cash value account
先看一个例子。Amy,35 岁女性,身体健康。她每个月放进去 $800,放 15 年,一共 $144,000。 保额是 $100 万。从第一个月存钱起,两个账户就同时生效:这一笔钱,进去之后分成两边。
Start with an example. Amy is 35, female, in good health. She puts in $800 a month for 15 years, $144,000 in all. The face amount is $1,000,000. From the first month's deposit both accounts are in effect: once that money goes in, it splits into two sides.
左边,是现金账户(Cash Value):
On the left is the cash value account:
- 按美股大盘(标普 500)的表现记息,钱本身不在股市里;演示表常用 6–7% 的假设利率,这是假设,不是保证;
- It is credited by reference to the U.S. market index (the S&P 500), though the money itself isn't in the market; illustrations commonly assume 6–7%, which is an assumption, not a guarantee;
- 碰上跌的年份,指数那部分记零,不记负数;但保单成本照扣,那一年现金值会略降;
- In a down year the index portion is credited zero, never negative; policy charges still come out, so the cash value dips slightly that year;
- 什么时候放、放多少,都比较灵活。
- When you put money in, and how much, is fairly flexible.
二、右边:保险账户2. Right side: the insurance account
右边,是保险账户(Face Amount)。人不在了,家人拿到 $100 万, 这笔钱一般不用交所得税。
On the right is the insurance account. If Amy dies, her family receives $1,000,000, generally free of income tax.
但它不只是身后才有用。人还活着的时候,得了大病,也能动用其中一部分, 能预支多少,条款里有上限,实际金额由保险公司在触发时按病情、年龄、剩余寿命计算,签单时给不出具体数字; 预支的钱从身故理赔里扣,不是额外多给。哪些病?末期疾病、慢性病、重大疾病、重大伤残,还有阿兹海默。 各项的触发条件见生前福利一文。
But it isn't only useful after death. While she's alive, a serious illness lets her draw on part of it. The rider sets a ceiling, and the actual amount is computed by the carrier at the time of the claim from the condition, age and life expectancy, so no figure can be quoted at sale; whatever is advanced comes out of the death benefit rather than on top of it. Which conditions? Terminal illness, chronic illness, critical illness, critical injury, and Alzheimer's. The triggers for each are in the Living Benefits article.
所以你看,同一笔钱,两件事同时在做。活着的时候,一边攒钱,一边保命; 走了以后,变成留给家人的一笔一般不用交所得税的钱。很多人会问:"那我到底是在买保险,还是在理财?" 答案是两者都在做。论收益它比不过最高收益的投资工具,论保障它也不是最便宜的, 它的长处是把两件事叠在一起,总成本比分开买低。
So the same dollars do two jobs at once. While you're alive they accumulate and protect; after you're gone they become money for your family that is generally free of income tax. People often ask, "So am I buying insurance or investing?" Both. It won't beat the highest-returning investment, and it isn't the cheapest protection; what it does is stack the two for less than buying them separately.
三、大盘只是一把尺子3. The index is only a ruler
刚才说现金账户跟着美股大盘走。这个大盘,指的是标普 500(S&P 500): 美国五百家最大的上市公司凑在一起,按市值算出来的一个数。全世界看美股,最常看的就是它。 它是 1957 年推出的;按市值加权,意思是公司越大分量越重:在某一时点,排第一的 Nvidia 约占 7.3%, 前十家合计约占 38%,这些权重每天随股价变动。
We said the cash value account follows the U.S. market. That market is the S&P 500: the 500 largest U.S. public companies, combined into a single number weighted by market value. It's the figure the world watches most when it watches U.S. stocks. It was launched in 1957; market-value weighting means the bigger the company, the more it counts. At one point in time, Nvidia at the top was about 7.3% and the top ten together about 38%, and those weights move daily with share prices.
接下来这句话很关键:你的钱,没有在股市里。 保险公司拿你的钱去买的是债券和期权。大盘只是一把尺子, 用来量今年该给你记多少利息。你的钱本身,不在里面。这句话带来两个结果:
The next sentence is the important one: your money is not in the stock market. The carrier uses it to buy bonds and options. The index is just a ruler that measures how much interest to credit you this year. Your money itself isn't in it. Two consequences follow:
- 第一,大盘跌,不会把你账户里的钱扣掉,这就是保底的来头;
- First, when the index falls, nothing is taken out of your account. That's where the floor comes from;
- 第二,大盘涨,你拿到的不含股息,而且有上限。
- Second, when the index rises, what you're credited excludes dividends and has a ceiling.
四、跌了要爬多久4. How long it takes to climb back
这一节是整个产品最核心的地方:跌的年份,指数那部分记零,不按跌幅往下扣 (保单成本照扣,见第六节)。为什么这件事这么重要?算笔账就知道。
This is the heart of the product: in a down year the index portion is credited zero rather than marked down by the drop (policy charges still apply; see section 6). Why does that matter so much? Run the numbers.
假设你有 $100 在股市里,今年跌了 30%,剩下 $70。明年要涨回 $100,需要涨多少? 不是 30%,是 43%。跌三成,要涨四成多才回本。跌得越多,爬得越久:
Say you have $100 in the stock market and it drops 30% this year, leaving $70. How much does it need to rise next year to get back to $100? Not 30%. It needs 43%. A 30% loss takes a gain of more than 40% just to break even. The deeper the fall, the longer the climb:
| 跌幅Drop | $100 剩$100 left | 回本要涨Gain to recover |
|---|---|---|
| 10% | $90 | 11% |
| 20% | $80 | 25% |
| 30% | $70 | 43% |
| 50% | $50 | 100% |
五、年度重置5. The annual reset
现在换成有保底的。跌的那一年,你记零。你没赚,但你也没退。 第二年大盘涨,你是从原来的位置往上走,不是从坑底往上爬。 团队里常说的"零就是英雄(Zero is the hero)",说的就是这件事。
Now switch to a floor. In the down year you're credited zero. You didn't gain, but you didn't go backwards either. When the index rises the next year, you climb from where you were, not from the bottom of a hole. That's what we mean on the team when we say "zero is the hero."
这个机制有个名字,叫年度重置(annual reset)。意思是, 每年年底的数字,就是明年的起跑线。跌掉的不用先补回来,因为指数那部分没有记负数。 但要说清楚:保单成本每月照扣,所以记零的年份,现金值还是会往下走一点。记住三个数字:
The mechanism has a name: the annual reset. Each year's ending value is next year's starting line. There's no drop to make back first, because the index portion was never credited a negative. Be clear, though: policy charges come out every month, so in a zero year the cash value still moves down a little. Three numbers to remember:
六、代价:封顶与保单成本6. The price: caps and policy costs
保险公司让你跌的时候不亏,它不是做慈善。它要留走你涨的时候的一部分。 这个代价,体现在两个地方。
The carrier keeping you whole in down years isn't charity. It keeps part of your upside in return. That price shows up in two places.
1)封顶(Cap)
1) The cap
基础策略一般封在 11% 左右。大盘今年涨了 25%?你拿到的还是 11%。 想要更高的上限,可以加附加条款(例如 Enhancer 系列), 最高的那一档,在 Living Life Defender 的独家条款下能到 17%。 但附加条款是要收费的,费用从现金账户里扣。
A base strategy is usually capped around 11%. The index gained 25% this year? You still get 11%. For a higher ceiling you can add riders (the Enhancer series, for example); the top tier reaches 17% under the Living Life Defender exclusive rider. But riders carry a charge, deducted from the cash value account.
2)保单成本(Cost of Insurance)
2) Cost of insurance
每个月从现金账户里扣一笔,这是保险本身的价钱,而且会随年龄上升。 这笔钱不是藏起来的,每年的对账单上都写着,你可以自己看。
Each month a charge comes out of the cash value account. That's the price of the coverage itself, and it rises with age. It isn't hidden: it's on your annual statement, where you can read it yourself.
现金账户不够扣保单成本的时候,保单会失效,也就是断保。两种情况会断: 一是保额定得太高、保费放得太少;二是好几年不放钱,同时还一直从里面借钱。 这两种,在设计的时候就能避开。国家人寿(National Life)还有专门的保证不失效附加条款, 可以当最后一道保险。所以设计比产品本身更重要,这也是为什么我们坚持在出方案之前把这一段讲清楚。
When the cash value account can't cover the charges, the policy lapses. Two things cause it: a face amount set too high with too little premium, or several years of no funding while loans keep coming out. Both can be avoided at the design stage, and National Life offers no-lapse guarantee riders as a last line of defense. Design matters more than the product, which is why we insist on explaining this part before presenting anything.
七、7702 与保单贷款7. Section 7702 and policy loans
很多人最关心这一条。依据是美国税法的一个条款,叫 7702。 它规定了:符合条件的人寿保险,里面的钱增长的时候不用交税(税法上叫延税)。
This is the part most people care about. It rests on one section of the U.S. tax code, IRC §7702. It says that inside a qualifying life insurance policy, growth isn't taxed as it happens (it's tax-deferred).
那拿出来呢?分两步:
And taking money out? Two steps:
- 先拿你自己放进去的本金。这部分本来就是你的钱,不用交税。
- First, take back the premiums you paid in. That was your money to begin with, so it isn't taxed.
- 本金拿完了,再往外拿,走的是保单贷款。
- Once the basis is used up, anything more comes out as a policy loan.
关键就在这儿:借钱,不算收入。你跟银行借钱,要交所得税吗?不用。同一个道理。
That's the key: a loan is not income. When you borrow from a bank, do you owe income tax on it? No. Same principle.
八、两类贷款8. Two kinds of loans
国家人寿的保单贷款分两大类:
National Life's policy loans fall into two broad kinds:
- 标准贷款(Standard Loan):从第 11 个保单年度开始, 借款利率和记息利率一样,等于一借一还两抵消。
- Standard Loan: from policy year 11, the loan rate equals the crediting rate, so the two cancel out.
- 参与型贷款(Participating Loan):你借出来的那笔钱,还留在保单里继续记息。 按利率方式又细分为固定、浮动、分红三种。指数表现好时能赚到利差, 指数记零的年份照样要付贷款利息,收益和风险都被放大。
- Participating Loan: the amount you borrow stays in the policy and keeps earning. It comes in three variants by rate type: fixed, variable, and declared. In a strong index year you can earn a spread; in a zero year you still owe loan interest, so both upside and risk are amplified.
四种具体方式的利率与取舍,见 保单贷款一文与 Living Life Defender 一文。
Rates and trade-offs for all four specific options are in the Policy Loans article and the Living Life Defender article.
九、两个前提9. Two conditions
免税取钱有两个前提,必须做到。第一,保单要一直有效,到人不在为止。 中途断掉,之前通过贷款取出的收益部分可能会在当年变成要交税。 第二,不能变成 MEC(Modified Endowment Contract)。 放钱超过法律规定的上限,整个税务待遇会彻底改变。 这两件事都是设计层面的技术活,做计划书的时候就要算清楚。
Tax-free access depends on two conditions, and both are non-negotiable. First, the policy must stay in force until death. If it lapses midway, gains previously taken out through loans can become taxable in that year. Second, it must not become a MEC (Modified Endowment Contract). Funding above the statutory limit changes the tax treatment entirely. Both are design-level work, to be worked out when the illustration is built.
十、回头看一遍10. Looking back
一份保单,两个账户:
One policy, two accounts:
左边 · 现金账户Left · Cash Value Account
- 攒钱:以标普 500 为尺子记息,利滚利
- Accumulates: interest measured against the S&P 500, compounding
- 跌了记零、不记负数(保单成本照扣);每年年度重置
- Zero, never negative, in down years (charges still apply); resets every year
- 增长延税;满足两个前提时,可以通过保单贷款免税取钱
- Growth is tax-deferred; when both conditions are met, money can come out tax-free via policy loans
右边 · 保险账户Right · Insurance Account
- 保命:身故理赔 $100 万
- Protects: a $1,000,000 death benefit
- 活着能用:大病可提前动用一部分
- Usable while alive: part can be accessed early for serious illness
- 走了以后:家人拿到的钱一般不用交所得税
- At death: your family generally owes no income tax on it
代价是封顶和保单成本,都写在明面上。免税的前提是保单不断,不变成 MEC。 这个东西不神秘,它就是一套规则。规则搞清楚了,它适不适合你,你自己心里就有数了。
The price is the cap and the policy costs, both out in the open. Tax-free access depends on the policy never lapsing and never becoming a MEC. There's nothing mysterious here; it's a set of rules. Once the rules are clear, you'll know for yourself whether it fits you.
本文仅供一般性财务教育使用,不构成保险、税务或投资建议;文中数字为说明性举例,具体保障与条款以保单为准。各州规则不同、法规逐年调整,采取行动前请咨询持证专业人士。
General financial education only, not insurance, tax, or investment advice. Figures are illustrative; the policy governs. Rules vary by state and change over time; consult a licensed professional before acting.